Klarna expands in-store and online reach with Fiserv
Hey Payments Fanatic!
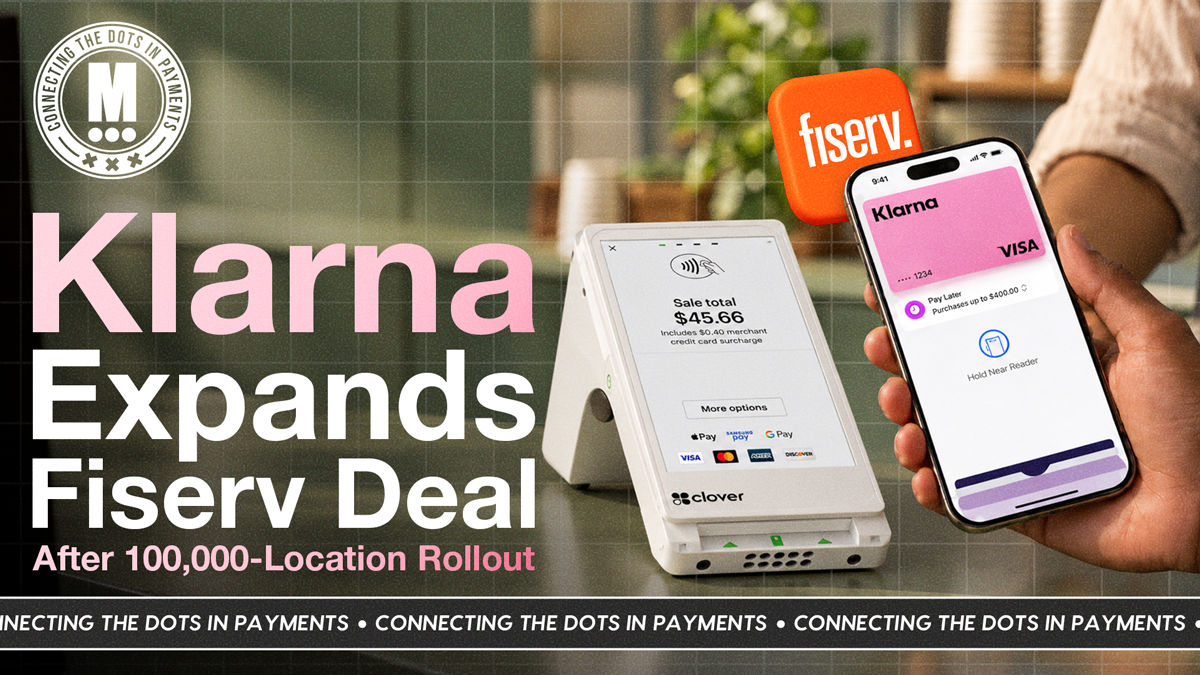
Buy now, pay later is moving further into physical retail, and Klarna is making a bigger push through Fiserv.
After going live at 100,000 U.S. merchant locations through Clover, Klarna is expanding its partnership with Fiserv to reach enterprise merchants through Commerce Hub. The deal will bring Klarna’s payment options to both online and in-store checkout across the U.S., Canada, the UK and select European markets.
Customers will be able to pay upfront, pay in 30 days or split purchases into interest-free instalments. For merchants, the move connects flexible payments across channels, while giving Klarna another route to expand its network beyond online shopping.
The bigger play is distribution: the easier Klarna is to offer wherever people shop, the closer it gets to becoming a mainstream payment option.
Here’s what else is happening in payments today👇
See you tomorrow!
Cheers,
INSIGHTS
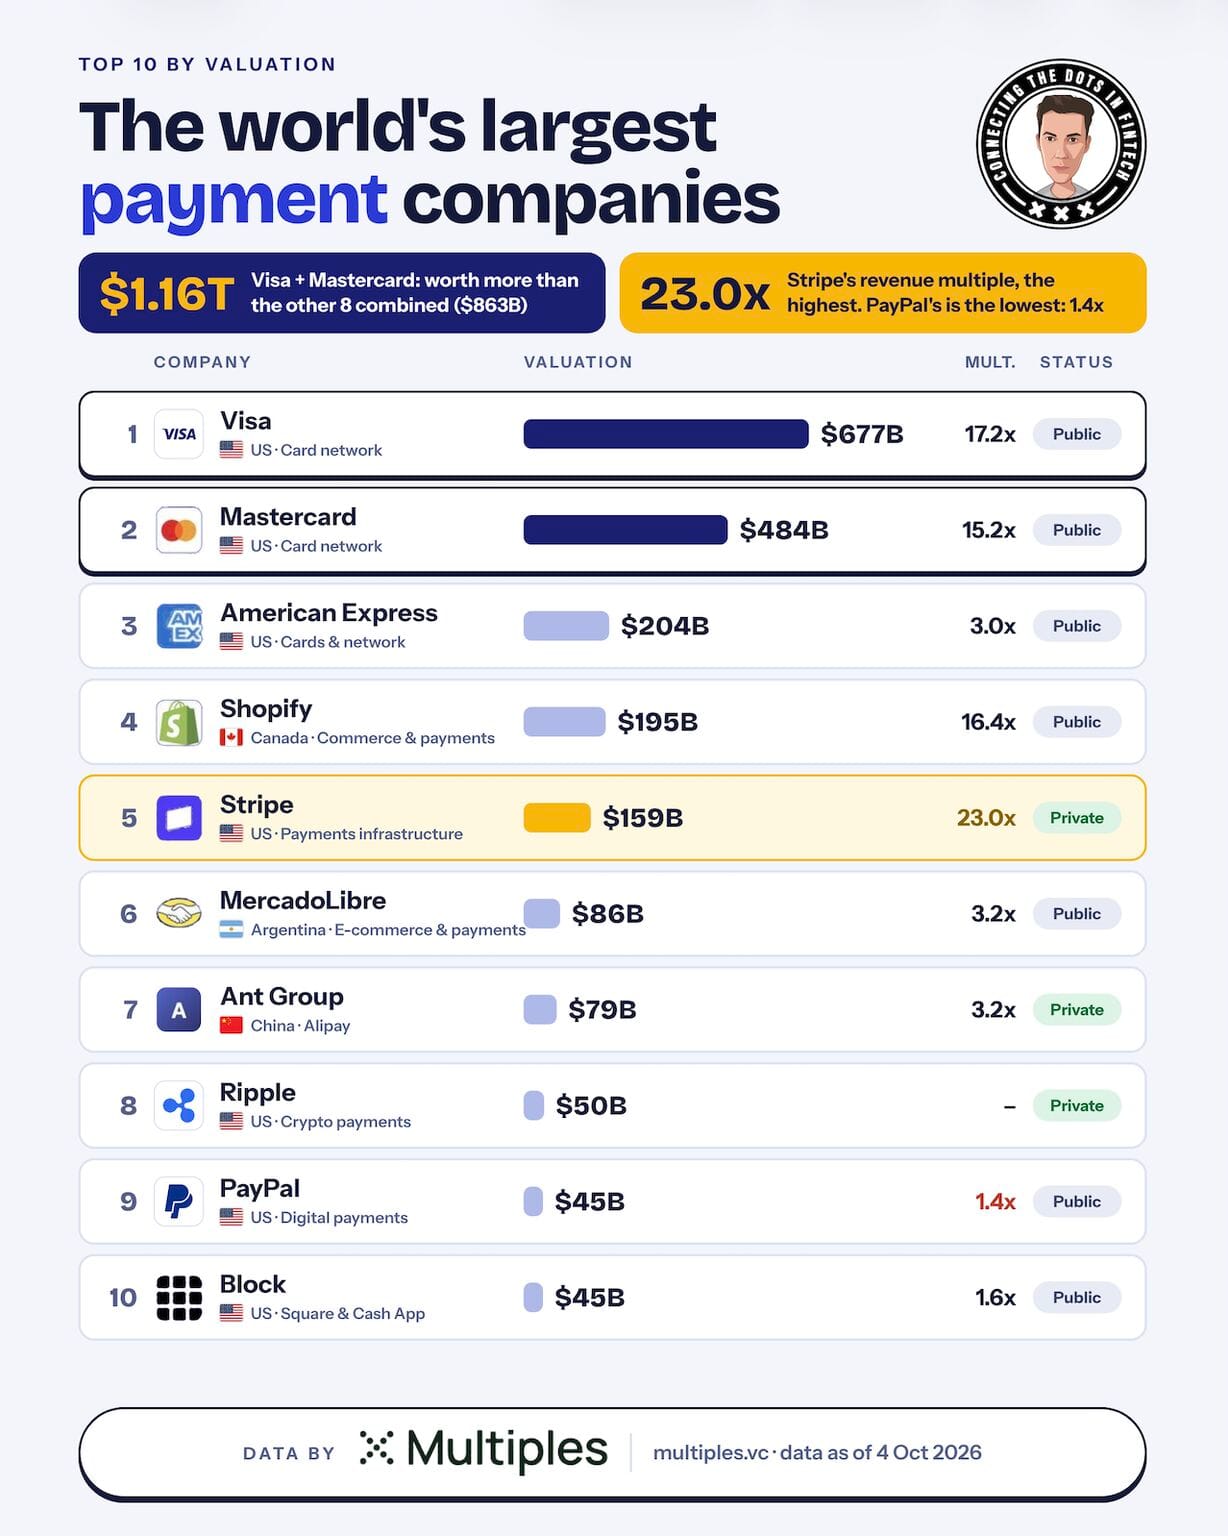
💡 The World’s Largest Payment Companies by Valuation. Visa and Mastercard have a combined valuation of $1.16 trillion, exceeding the other eight companies in the top 10 combined. Stripe ranks fifth at $159 billion and leads the list by revenue multiple at 23x, while PayPal has the lowest multiple at 1.4x. The ranking also highlights the global mix of players shaping the payments industry, from American Express and Block to Brazil’s MercadoLibre and China’s Ant Group.
NEWS
🇺🇸 Klarna expands its Fiserv partnership to enterprise merchants, after going live at 100,000 U.S. locations via Clover. Klarna will be available on Commerce Hub for the first time, both in store and online. Merchants in the U.S., Canada, the U.K. and select European markets will be able to offer pay in 30 days or interest free installments.
🌍 Mastercard partners with Moovn to expand digital payments across East Africa. The five-year collaboration will extend prepaid cards, digital wallets, merchant acceptance and cross-border transfers across the region. Read more
🌎 Mastercard introduces risk intelligence to enable more secure stablecoin payments. Stablecoin Security launches in North America with Borderless.xyz and Keyrails as initial partners. It flags fraud, scam and sanctions risk before funds move on-chain.
🇺🇸 zerohash launches AUTH to simplify onchain movements. Users can link accounts directly instead of using wallet addresses. AUTH offers 600+ connections reaching about 250 million users across 190+ countries.
🌎 dLocal data shows local payment methods can lift merchant transaction growth by up to 55%. One merchant in Brazil saw total volume rise 55% within five months of adding Pix. In Peru, Yape overtook cards and drove total transaction volume up more than 25% over six months.
🇸🇬 Thunes and Coinbase partner to drive next generation global payments. Coinbase will integrate Thunes' Direct Global Network for payouts to local clearing systems. Thunes will use Coinbase's stablecoin infrastructure for its global network.
🌎 MoneyGram launches a single global experience for moving and managing money. The updated app and website combine digital money movement, cash access through its retail network and stablecoin powered capabilities. In select markets, consumers can also hold a stable, dollar denominated balance.
🇺🇸 Fuze Finance partners with Modern Treasury's payments infrastructure for U.S. expansion. The integration provides access to named U.S. accounts in over 100 countries, alongside ACH, FedNow and RTP payment rails. It also enables transfers between U.S. dollars and stablecoins, supporting Fuze's expansion into the U.S. market.
🇦🇷 Clara launches commercial operations in Argentina, as part of its expansion across Latin America. The corporate payments and spend management platform also introduced Clara Global in the country and opened the search for a Country Manager. Clara Global automates between 80% and 90% of expense approvals and rejections.
🇺🇸 Fiserv makes Commerce Hub globally available for enterprise merchants. The platform gives businesses a single integration to access local payment methods, acquiring and commerce services across markets. Commerce Hub is growing more than 100% YoY and offers unified settlement, reconciliation and reporting.
🇮🇹 Satispay launches its Red debit card without a subscription for over 6.5 million users. The release follows nearly 100,000 card requests within weeks of the initial launch, as Satispay surpasses 650,000 IBANs. The account also offers free instant SEPA transfers and interest free installments with Paga in 3.
🌍 Getnet partners with PingPong to support its expansion into Iberia. The collaboration combines PingPong's cross border B2B infrastructure with Getnet's European acquiring and access to local payment methods like Bizum and MB WAY. PingPong supports over 750,000 businesses and processes over $300bn annually.
🇺🇸 Block selects Marqeta to enable Square Credit Card on the American Express Network. Square will consolidate debit, prepaid, and credit programs on one platform. Existing Square Card accounts will migrate without disrupting cardholders.
🇺🇸 Euronet and Fireblocks extend their partnership to bring stablecoins into card issuing. Banks and FinTechs can launch stablecoin funded card programs on Euronet's Ren and CoreCard platforms. Fireblocks provides the embedded wallet infrastructure that holds and moves the underlying balances.
🌎 Mesh partners with Visa to make stablecoin and crypto balances spendable at 175M merchants. Consumers can pay directly from existing wallet app balances across more than 200 countries and territories.
🇵🇭 Paymentology secures a strategic deal to power Asia United Bank's digital payments in the Philippines. Its issuing and real-time processing platform will support AUB's HelloMoney wallet, mobile banking and QR Ph.
🇺🇸 Matera, Payfinia and Solana Foundation demonstrate new U.S. QR code payment standard at Money20/20. Customers can pay invoices over FedNow, RTP, or USDC on Solana. Funds arrive within seconds and invoice records update automatically.
🇧🇹 StoneX launches Bhutanese Ngultrum payments on its global network, expanding frontier market access. Eligible StoneX Payments clients can facilitate transactions in local currency. The network covers more than 140 currencies and 180 countries.
🇺🇸 NewtekOne's bank subsidiary launches Zelle for small businesses, adding instant payment options. Eligible clients can send and receive payments through the Newtek Advantage portal. Newtek Bank also joined the FedNow and RTP receiving networks.
🇬🇧 Apple faces a potential legal battle in the UK over iPhone tap-to-pay rules. The Competition and Markets Authority plans to require Apple to give competing payment providers access to its digital wallet technology, potentially widening competition in contactless payments.
🌎 KORT Payments agrees to acquire AptPay, expanding real time payments and payment orchestration across North America. AptPay offers a single integration across rails including Interac e-Transfer, RTP, FedNow and ACH. The deal extends KORT beyond card acceptance into A2A payments and disbursements.
🇺🇸 JPMorgan brings its JPM Coin deposit token to Ethereum for institutional clients. Representing US dollar deposits held at the bank, the token enables 24/7 transfers within seconds and can support blockchain payments and settlement of tokenised assets.
🇺🇸 Proof launches x401, an open protocol letting websites verify who AI agents represent. Consumers can authorize wire transfers, purchases and payment mandates through Proof's agent identity wallet. Its MCP server works with Grok and Claude.
🇿🇦 South Africa will open its national payments system to fintechs, retailers and telecoms in 2027. The reform will allow non-bank providers to connect directly to payment infrastructure, reducing reliance on banks as intermediaries.
GOLDEN NUGGET
When you make an 𝐨𝐧𝐥𝐢𝐧𝐞 𝐩𝐚𝐲𝐦𝐞𝐧𝐭, do you know how many parties are involved and who they are?
Let’s break it down:
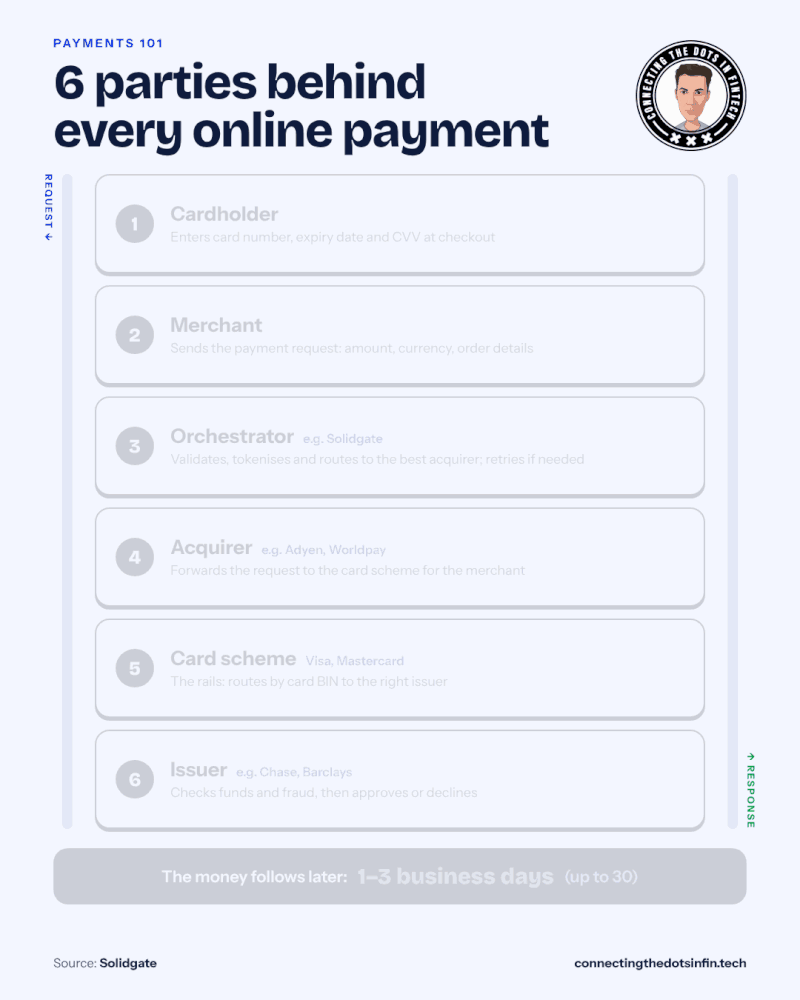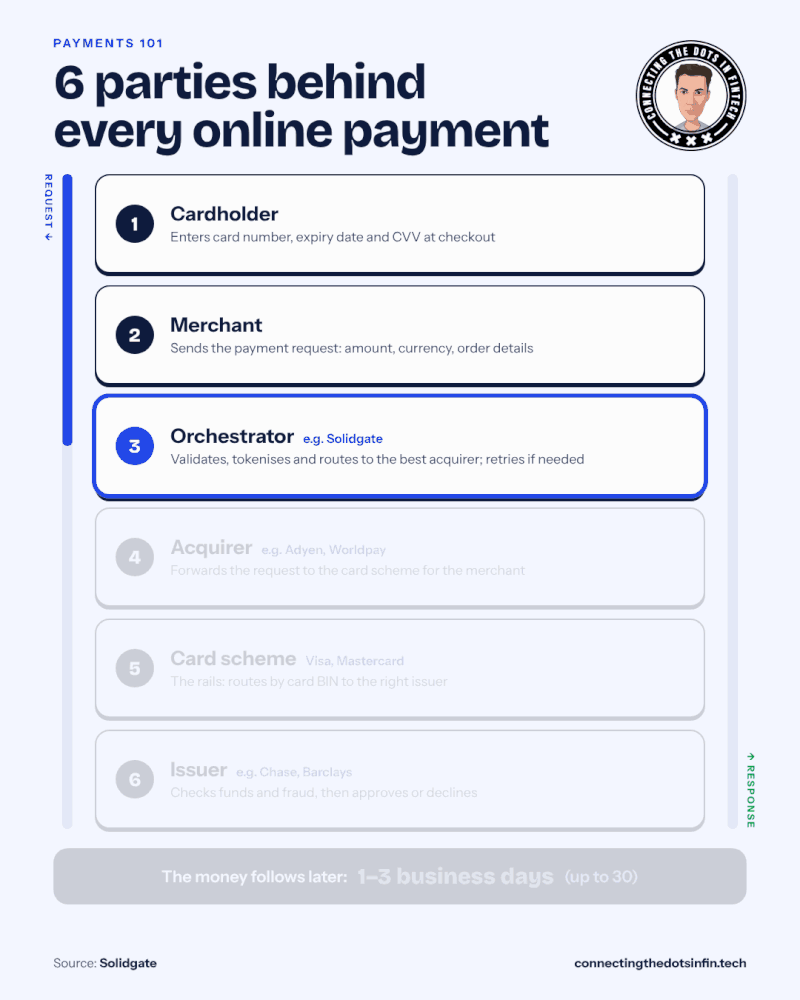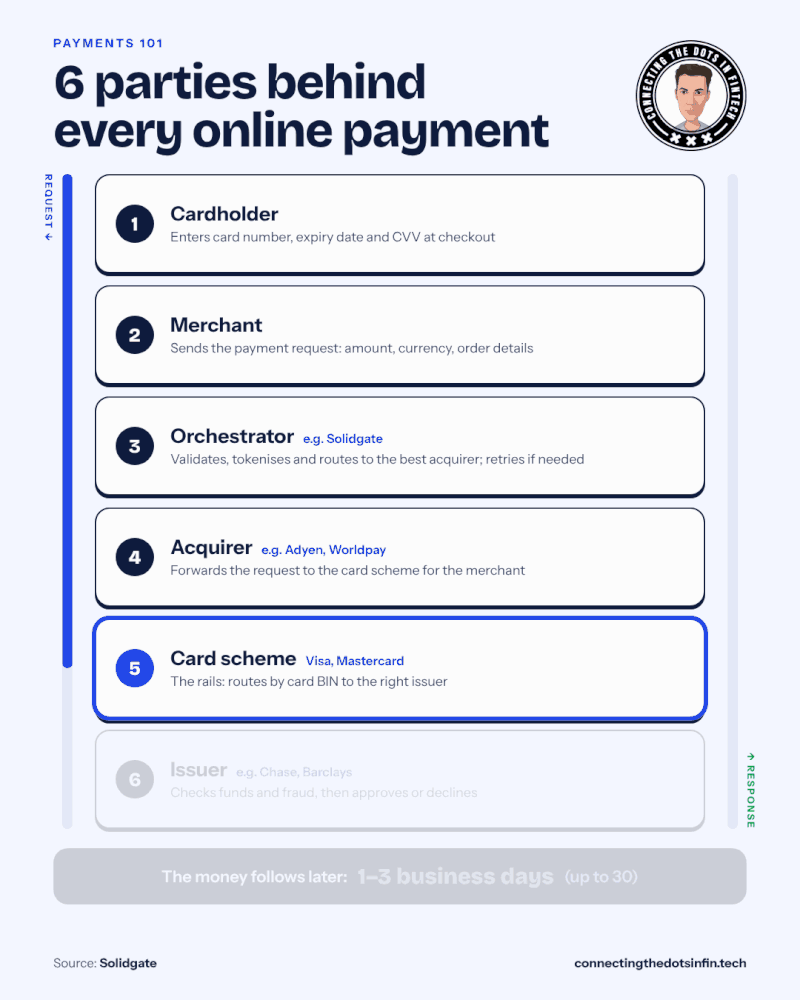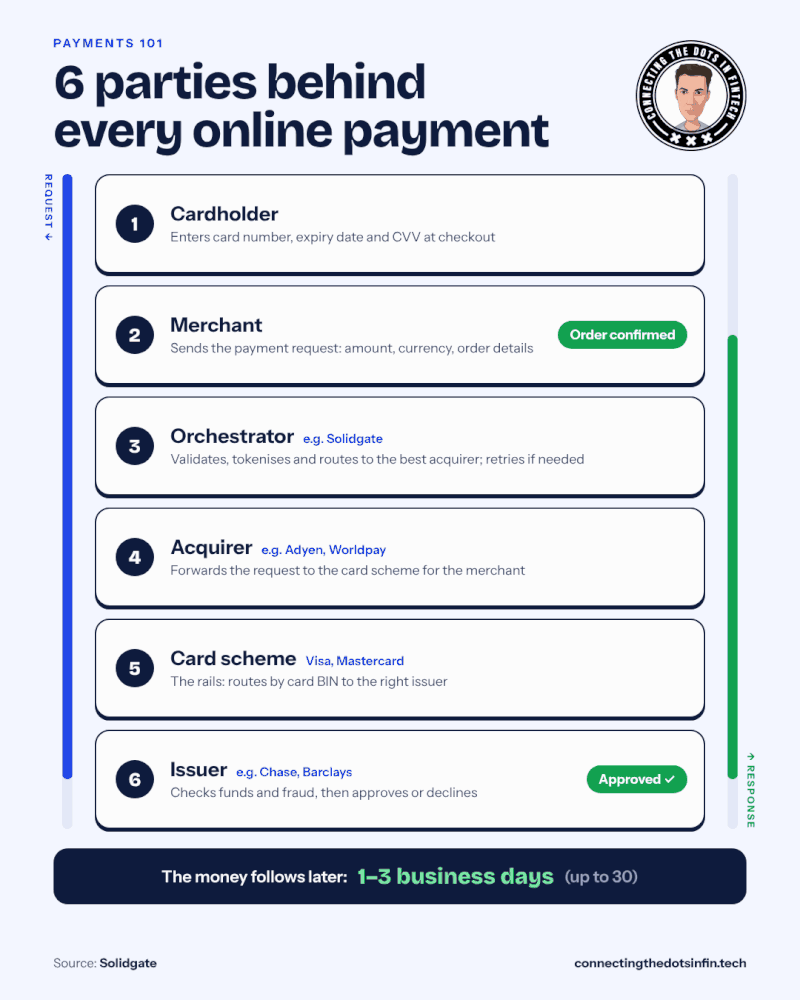
1️⃣ 𝐂𝐚𝐫𝐝𝐡𝐨𝐥𝐝𝐞𝐫 (𝐜𝐮𝐬𝐭𝐨𝐦𝐞𝐫)
First, a customer enters their card details (PAN, expiration date, CVV) on a merchant’s website or app to buy something.
2️⃣ 𝐌𝐞𝐫𝐜𝐡𝐚𝐧𝐭
The merchant collects card info via a checkout form and sends a payment request—including order details, amount, and currency—to a Payment Orchestrator.
3️⃣ 𝐎𝐫𝐜𝐡𝐞𝐬𝐭𝐫𝐚𝐭𝐨𝐫/𝐏𝐚𝐲𝐦𝐞𝐧𝐭 𝐎𝐫𝐜𝐡𝐞𝐬𝐭𝐫𝐚𝐭𝐢𝐨𝐧 𝐏𝐥𝐚𝐭𝐟𝐨𝐫𝐦 (e.g. Solidgate)
The Payment Orchestrator links merchants and providers, routing transactions efficiently by validating card data, choosing optimal acquirers, handling retries, and managing 3DS if needed.
4️⃣ 𝐀𝐜𝐪𝐮𝐢𝐫𝐞𝐫 (e.g. Adyen, Worldpay)
The acquirer enables card payments by receiving and forwarding requests through card schemes, acting as the merchant, and settling funds once authorized.
5️⃣ 𝐂𝐚𝐫𝐝 𝐒𝐜𝐡𝐞𝐦𝐞 (Visa, Mastercard)
Card schemes serve as the “payment rails” linking acquirers and issuers, routing transactions via the card BIN and performing risk, fraud, and compliance checks.
6️⃣ 𝐈𝐬𝐬𝐮𝐞𝐫’𝐬 𝐁𝐚𝐧𝐤 (e.g. 𝐂𝐡𝐚𝐬𝐞, 𝐁𝐚𝐫𝐜𝐥𝐚𝐲𝐬)
The cardholder’s bank steps in to do a quick background check: Is the card real? Are there enough funds or credit? Does anything look suspicious?
If all’s clear, it gives the green light with an authorization code. If not, it shuts it down with a reason.
The merchant gets the answer—approved or declined—and if it’s a yes, the order moves ahead.
The actual money follows behind, settling in the next couple of business days.
🔁 𝗧𝗵𝗲 𝗣𝗮𝘆𝗺𝗲𝗻𝘁 𝗙𝗹𝗼𝘄: Cardholder → Merchant → Orchestrator → Acquirer → Scheme → Issuer → Scheme → Acquirer → Orchestrator → Merchant
💵 𝗦𝗲𝘁𝘁𝗹𝗲𝗺𝗲𝗻𝘁 𝘁𝗶𝗺𝗲 can range from 𝟭 𝘁𝗼 𝟯𝟬 𝗱𝗮𝘆𝘀, depending on:
► Payment method: Cards settle faster than bank transfers or ACH.
► Acquirer/Processor: Some process payments quicker than others.
► Card scheme: Visa, Mastercard, Amex vary, especially for cross-border transactions.
► Country amp; currency: International payments take longer due to conversions and regulations.
► Merchant account type: High-risk or new merchants may face delays from compliance checks.
► Transaction type: Refunds, chargebacks, and disputes take longer.
► Weekends/holidays: Most banks and processors don’t settle payments during these times.
► Clearing time: Depends on the bank’s processing speed.
👉 More of this, and the latest Payments news in my newsletter
Trusted reach among senior decision-makers in FinTech, Payments & Banking.
👉 Explore Partnership here


Comments ()