US Court Strikes Down the Fed’s Debit Card Fee Cap

Hey Payments Fanatic!
Big news for the US payments industry: a federal appeals court has struck down the Fed’s 15-year-old rule on debit card interchange fees. The Eighth Circuit ruled that the Federal Reserve went beyond its authority when deciding which costs banks could include in their fee calculations.
At the heart of the dispute is the Durbin Amendment. Under Regulation II, large financial institutions can collect 21 cents per debit transaction, plus a percentage of the transaction value and an extra cent for fraud prevention. The court says the Fed’s approach went beyond what Congress intended, and the regulator must now rewrite the rule.
So who wins here? Retailers have challenged the fee structure, arguing that the rules allow banks to charge more than they should. Banks, meanwhile, say tighter caps could leave them covering more of the costs of fraud prevention, transaction processing and customer data protection, potentially affecting the services and benefits they offer.
But this isn’t the end of the story. The ruling could reshape the economics of debit payments in the US, and a similar case is still being considered by another federal appeals court. For banks, merchants and payment providers, the next chapter will be worth watching.
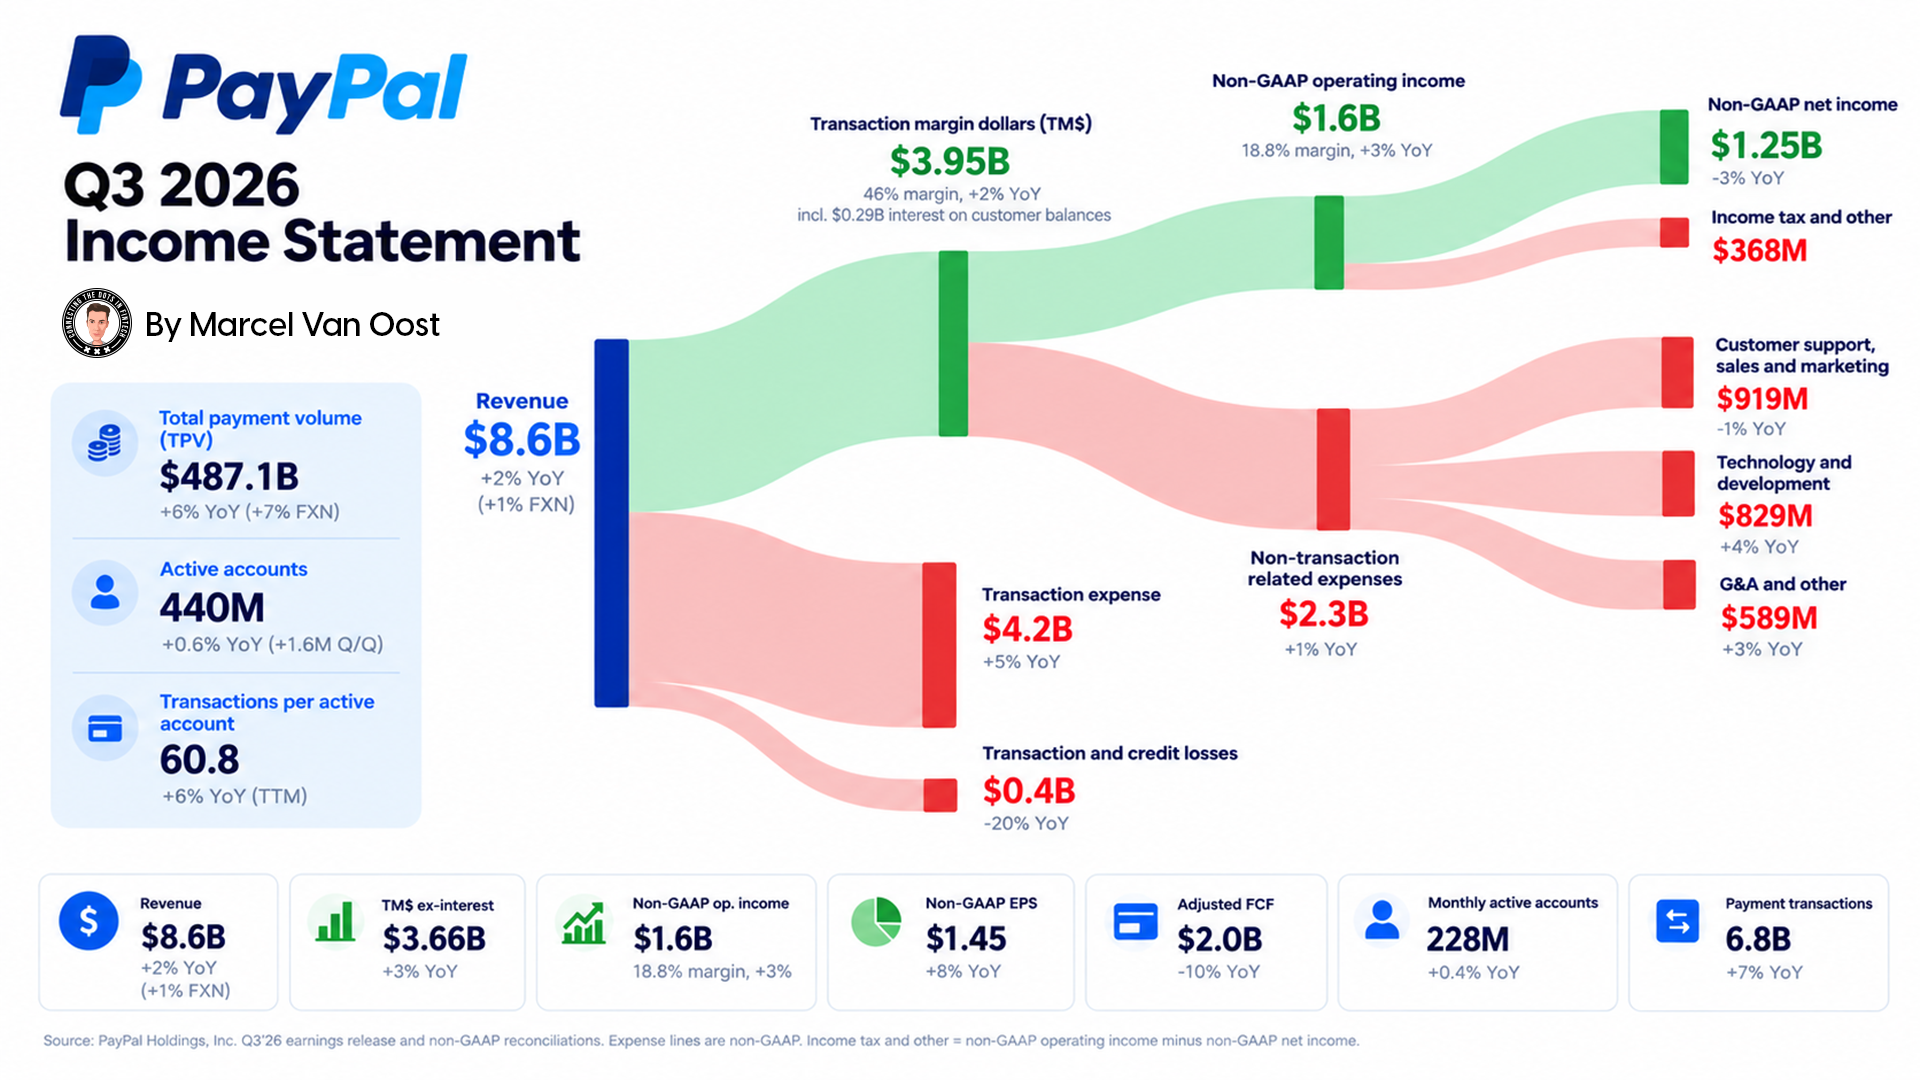
And speaking of payment volumes, PayPal’s Q3 2026 results show Venmo and Braintree leading the growth, while branded checkout remains sluggish and restructuring weighs on profits. Here’s how the numbers are shaping up.
Here’s what else is happening in payments today👇
See you tomorrow!
Cheers,
INSIGHTS
💡 PayPal Q3 2026: Venmo Pulls Ahead as Restructuring Shows Up in the Numbers. PayPal reported $487.1B in total payment volume (+6% YoY) and $8.58B in revenue (+2%), with Venmo TPV growing 14% and Braintree continuing to deliver double-digit growth. Branded checkout rose just 1%, marking its fourth consecutive quarter of modest growth and suggesting stabilization rather than a full recovery. Meanwhile, restructuring costs pushed GAAP operating income down 8% to $1.4B, even as non-GAAP operating margin improved slightly. The takeaway: Venmo and Braintree are driving payment volumes while PayPal works to simplify operations and improve profitability. Read the full analysis here
NEWS
🇺🇸 Klarna partners with Squire for barbershop instalment payments. The Stripe-powered integration lets customers booking services through Squire choose to pay in full, split payments into four interest-free instalments or access financing for larger purchases.
🌏 Mastercard expands Max benefits assistant focus to Asia Pacific issuers. Citi is exploring its use in Singapore and Hong Kong, as Mastercard encourages regional banks to adopt the AI-powered card benefits assistant to deliver personalised rewards recommendations and improve cardholder engagement.
🇧🇩 UCB, Mastercard and Grameenphone introduce co-branded payment sticker. The prepaid sticker can be attached to a smartphone or another item, allowing users to make contactless payments by tapping it at POS terminals. Cardholders can also access cashback, rewards and other benefits.
🇪🇹 Mastercard extends AI and tokenisation security in Ethiopia. Its fraud monitoring systems evaluate transactions using AI, while tokenisation substitutes card details with secure identifiers across digital payment channels.
🇰🇷 Woori Bank expands Samsung Wallet Money overseas payments. A tie-up involving Mastercard extends contactless acceptance to more than 150 million merchants in 210 countries and territories, according to the reported rollout.
🌍 Bolt is building Bolt Money with Airwallex, a financial offering for drivers and couriers. Partners would get a wallet, spending card, and access to their Bolt earnings, building on an existing relationship in which Airwallex initially supported Bolt's driver payouts in Canada.
🌍 MassPay chief executive outlines global money movement infrastructure strategy. Co-founder and CEO Ran Grushkowsky said the company uses multiple payment rails, banking partners and stablecoin networks to support international collections and disbursements. Its payment orchestration infrastructure automatically reroutes failed transactions, with MassPay maintaining 15 US sponsor bank relationships and more than 80 correspondent banking relationships.
🇺🇸 US appeals court strikes down Federal Reserve debit interchange cap. The Eighth Circuit ruled that the regulator exceeded its authority in calculating permitted bank costs under the Durbin Amendment; the Fed must reconsider the framework following the court ruling.
🇳🇱 Revolut Pay partners with Just Eat Takeaway.com on rewards. Customers can earn five times the usual RevPoints on qualifying food orders paid through Revolut Pay from October 28 to December 27, 2026, with the reward rate dropping to twice the usual points afterward.
📊 Visa posts $12.1 billion fourth-quarter net revenue. Quarterly net revenue increased 13%, with payments volume rising 9% and processed transactions up 10% in constant dollars; GAAP net income reached $6.0 billion according to the earnings report.
🌏 Google Wallet prepares Alipay+ QR payments for international travellers. An examination of Google Wallet's Android app revealed development work on a feature called Traveler QR, designed to enable QR payments through Alipay+ partner networks.
🇳🇱 Adyen reports €738.1 million third-quarter revenue and lowers margin outlook. Revenue rose 23% year on year and processed volume reached €451.1 billion; accelerated investment led Adyen to forecast a 50% EBITDA margin for 2026, down from around 52%, according to its business update.
🇲🇾 Malaysia expands overseas DuitNow QR payments through Alipay+. PayNet’s new outbound connection enables customers of participating Malaysian banks to pay at merchants in China, Hong Kong, South Korea, the Philippines and Laos using existing banking apps.
🇺🇸 Stripe launches free instant B2B transfers through Stripe Pay. The new plug-in lets businesses send funds using Stripe profile handles, without transfer fees. Available through Stripe Dashboard and CLI, it requires senders to have a funded financial account and recipients to have an account linked to their Stripe profile.
🇬🇧 PayPal and Revolut weigh in on UK scrutiny of Apple contactless access. The companies have contributed to debate over Apple’s tap-to-pay rules as UK authorities examine competition and access to mobile payment capabilities through the regulatory process.
🇺🇸 MoneyGram selects AiPrise for global verification operations. The payments company will use AiPrise’s AI-enabled platform for selected verification and fraud controls, drawing on more than 100 data sources through the implementation partnership.
GOLDEN NUGGET
Your card has no battery. No power source at all. Yet it just paid for your coffee.
How?
Everything happens in about 300 milliseconds:
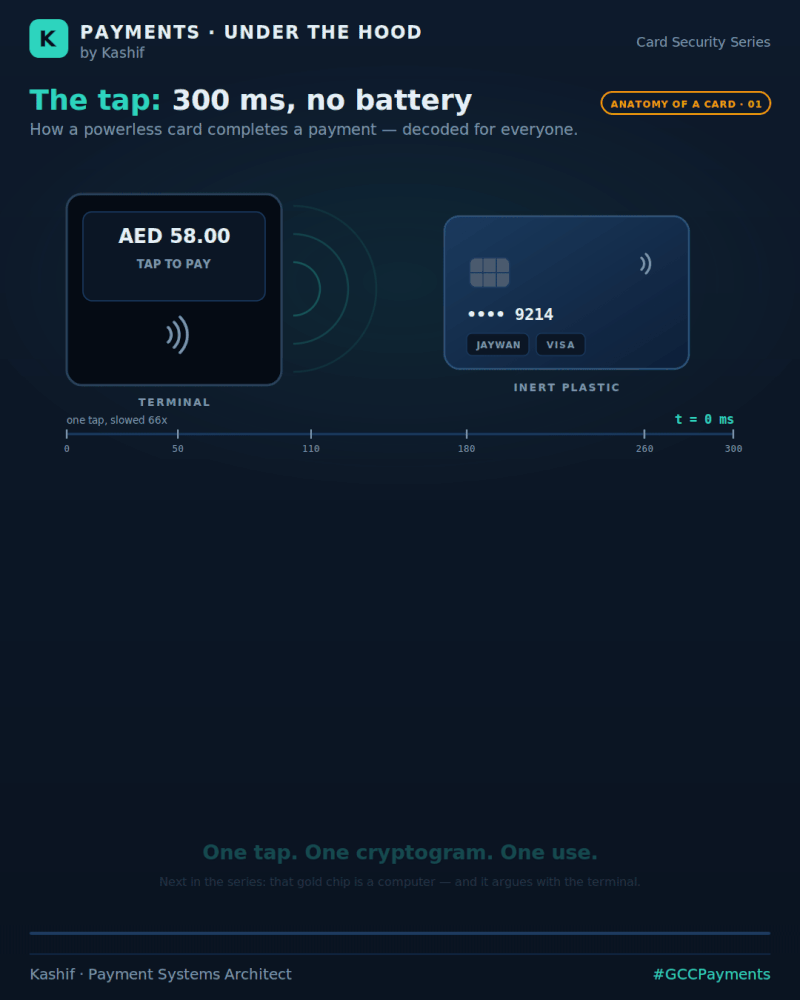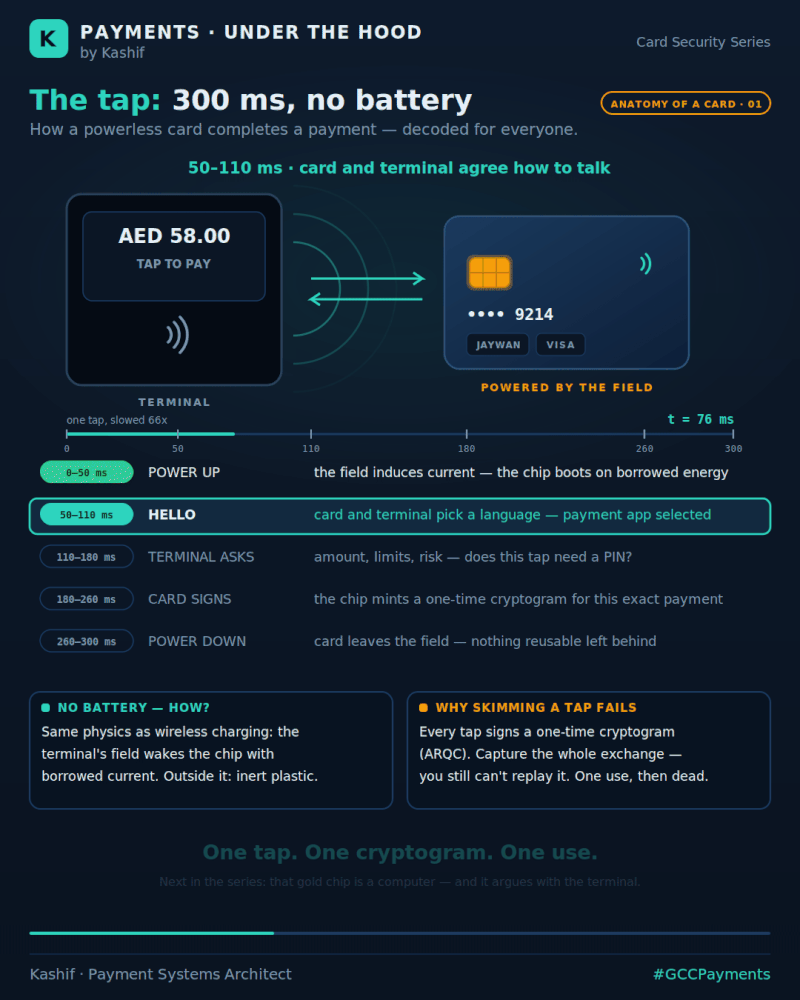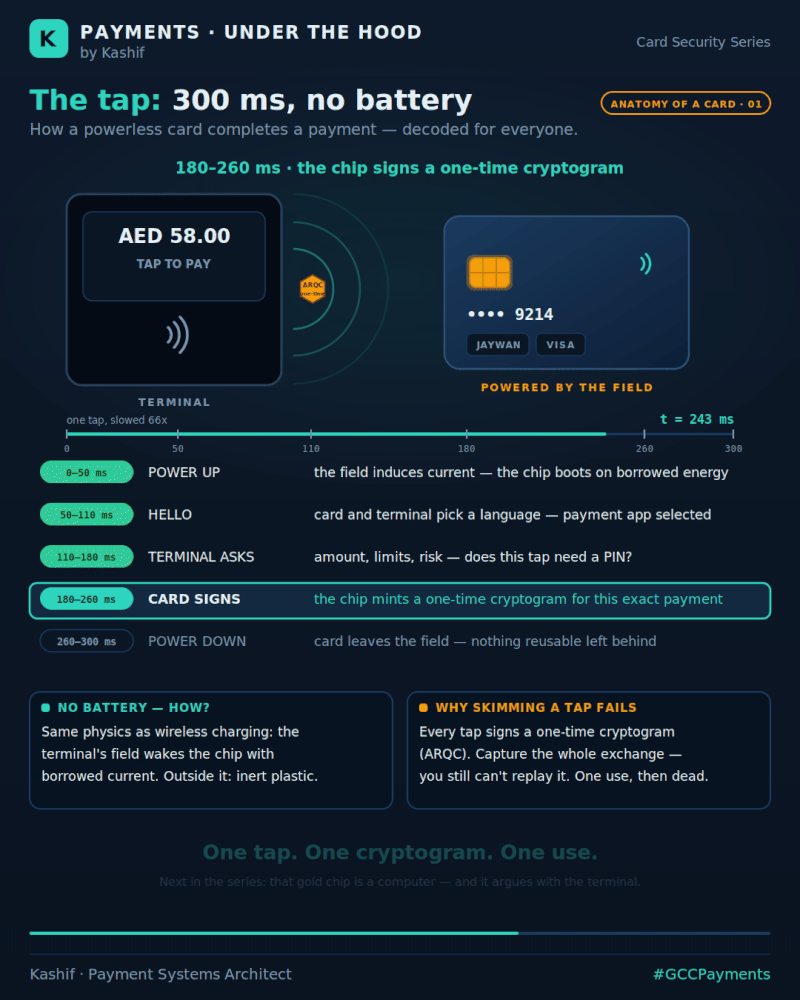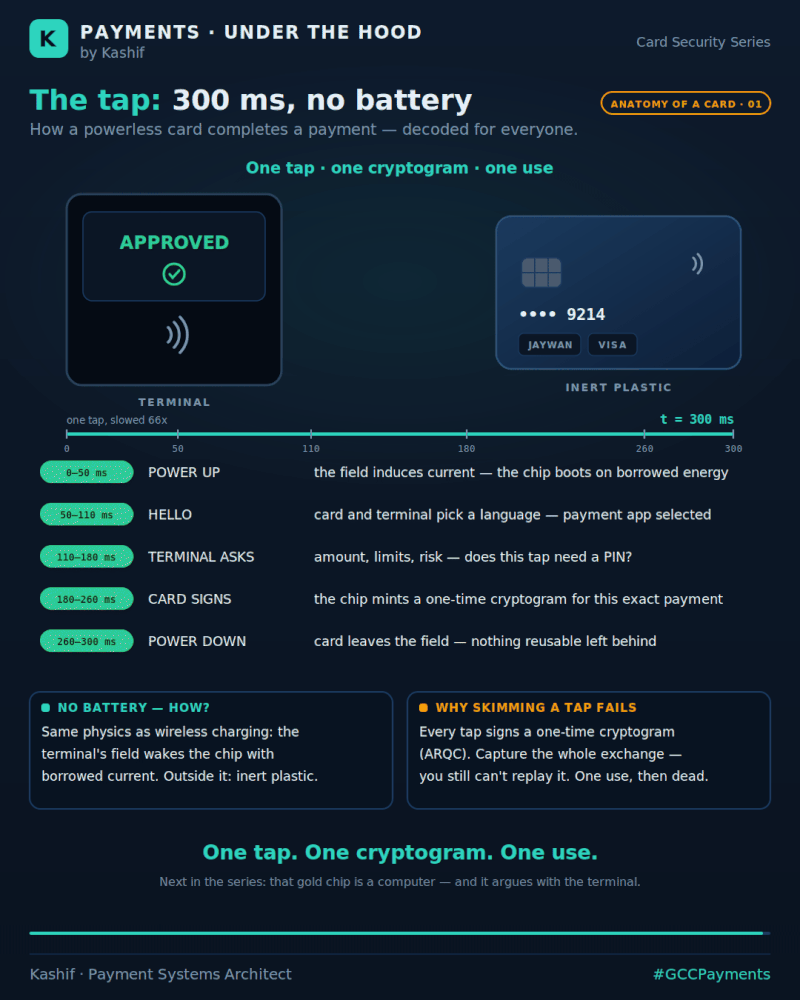
Here’s what happens during a single tap:
→ 0–50 ms · Power up
The terminal’s electromagnetic field induces a current in the card’s antenna.
The chip boots on borrowed energy, the same basic physics behind wireless charging.
→ 50–110 ms · Hello
The card and terminal establish how they’ll communicate and select the payment application.
→ 110–180 ms · The terminal asks
Amount. Currency. Limits. Risk checks.
Does this tap need a PIN?
→ 180–260 ms · The card signs
The chip creates a one-time cryptogram — the ARQC — for that exact payment.
One payment. One proof.
→ 260–300 ms · Power down
The card leaves the electromagnetic field and the chip shuts down again.
Inert plastic, until the next tap.
And this is perhaps the coolest part:
That one-time cryptogram is why simply capturing the contactless exchange isn’t enough to replay the same payment.
It was created for that transaction.
One tap. One cryptogram. One use.
All of this happens in around 300 milliseconds.
Source: Muhammad Kashif’s Payments Under the Hood series.
Trusted reach among senior decision-makers in FinTech, Payments & Banking.
👉 Explore Partnership here


Comments ()