Airwallex expands across global payments

Hey Payments Fanatic!
Airwallex has announced two partnerships that show how it’s becoming a bigger part of the infrastructure behind global business.
First, Airwallex is partnering with OpenTable to help its network of 70,000+ restaurants manage payments across markets. The deal also supports deposits and prepaid dining experiences, which OpenTable says reduce no-shows by 45% and late cancellations by 66%.
The second partnership is with Boost Payment Solutions, focusing on more efficient international B2B card payments. The results are already impressive: payment volume processed for Boost through Airwallex grew nearly 10x in five months, with more than 270 supplier accounts onboarded.
Different industries, same challenge: moving money across borders without adding complexity. Airwallex is building the infrastructure to help businesses do just that.
Here’s what else is happening in payments today👇
See you tomorrow!
Cheers,
INSIGHTS
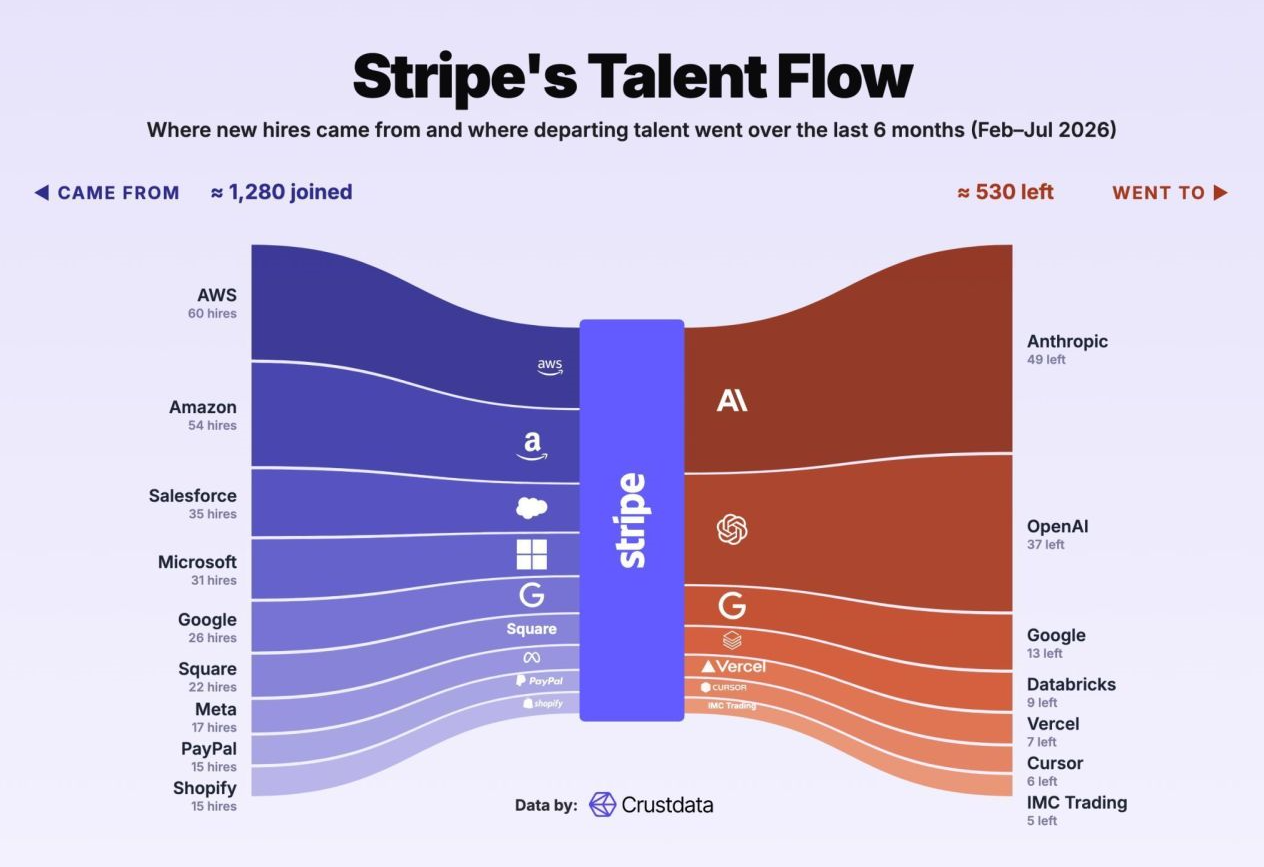
💡 Stripe’s UK Employees Earn £325,000 in Average Total Compensation. New company filings show that Stripe’s UK arm paid an average salary of £180,800, rising to £325,000 when share-based payments and pension contributions are included. Talent flows also reveal how competitive the market has become: around 1,280 people joined Stripe in six months, coming from 760 different companies, while approximately 530 left. AWS, Amazon, Salesforce, Microsoft and Google were among the biggest sources of new hires, while Anthropic and OpenAI were the top destinations for departing employees. The trend highlights Stripe’s ability to attract Big Tech talent, and the growing pull of AI companies.
NEWS
🌐 Boost Payment Solutions expands global B2B payments capabilities with Airwallex. Boost's volume processed through Airwallex grew nearly 10x in five months. The integration can onboard international suppliers in as few as two business days.
🌎 Airwallex and OpenTable partner to serve restaurants globally. Launch covers the US and Canada, with Australia and Mexico planned later this year. Airwallex will power reservation deposits and prepaid Experiences for OpenTable restaurants.
🇸🇾 Mastercard launches Mastercard Gateway in Syria for secure digital payments. The platform processes payments across POS and ecommerce channels via Merchant Cloud. It follows the first international card transactions in Syria in over a decade.
🇦🇷 Mastercard launches World Legend in Argentina, debuting The Mastercard Collection benefits platform. Cardholders get access to premium lounges at Ezeiza and Aeroparque airports. Travel assistance covers up to USD 1 million.
🇸🇦 Mastercard partners with Enjaz to expand card products and digital payment experiences in Saudi Arabia. The collaboration will introduce new card offerings for individuals and businesses, targeting expatriates, frequent travellers and high-net-worth customers.
🌍 Klarna launches Consumer FX, letting shoppers pay merchants worldwide in their own currency. Merchants can reach 120 million consumers in 26 countries with no new integration. Early results show a 5% lift in conversion and 6% in sales.
🇨🇦 Klarna expands its Zoom integration to Canada. Canadians can now pay for Zoom Workplace subscriptions through Klarna in full or in four interest-free installments. The relationship is already live in the U.S., UK, and Europe.
🇬🇧 Checkout.com expands into in-store payments with Mollie as a partner. The solution works with merchants' existing payment terminals and brings online and in-person transactions onto one platform. Mollie will integrate Checkout.com's acquiring infrastructure into its own payment offering.
🌐 Sierra and Stripe partner to let AI agents take payments during calls. Customers can talk, pay and get a receipt on the same call. Businesses can connect their Sierra agents to Stripe directly through the Stripe App Marketplace, without custom integrations.
🇺🇸 Visa announces enhanced capabilities for trusted business payments. A live pilot with BILL and Billtrust lets trusted AI agents complete approved invoice payments. Visa also introduced SESA 2.0 and Visa Commercial Fraud Solutions for virtual cards.
🌍 OpenFX introduces multi-currency accounts for FinTechs. The offering starts with named USD accounts and access to over 25 local payment rails, allowing businesses to manage cross-border payments and currency conversions through one platform. Additional currencies are planned.
🇮🇱 Nuvei enters the Israeli payments market with a local clearing license. The approval allows merchants, including Shein, Temu and KLM, to process payments locally in Israeli shekels, expanding Nuvei's domestic payment processing capabilities. The move comes as Nuvei prepares for its proposed $2.75 billion combination with Payoneer.
🇻🇪 Thunes expands its Direct Global Network into Venezuela. Members can send instant transfers to millions of Venezuelan bank accounts via Credito Inmediato Interbancario. Remittances to Venezuela reached an estimated US$6 billion in 2025.
🇬🇧 Corpay Cross-Border becomes the Official FX Partner of Newcastle United. The multiyear deal delivers FX risk management for the club's daily operations. Its platform will also let the club manage global payments through one access point.
🇦🇷 Argentine paytech Rebill closes a $5.4M pre Series A round. The raise takes its total funding past $9M since its 2020 founding. Rebill now operates in Argentina, Brazil, Chile, Colombia, Mexico and the US. Read more
🇸🇩 EdfaPay and GoPravo launch SDPay to expand digital payments in Sudan. The 50/50 joint venture pairs Saudi payment technology with local Sudanese expertise. SDPay will offer QR, POS, online gateways, wallets and remittances. Continue reading
🇺🇸 Ordr launches Ordr Insights at Money20/20, turning payments into customer intelligence. The AI suite can replace loyalty programs, apps and customer data platforms. It is available today across the United States and Canada.
🇺🇸 Ramp acquires treasury management platform Vesto. The acquisition brings external bank accounts and Ramp Banking into one view, allowing finance teams to monitor cash positions, analyze transactions and forecast liquidity across accounts.
🇹🇼 DBS PayLah! users can now scan to pay at Taiwanese merchants via TWQR. More than three million users can pay at over 250,000 participating merchants. Acceptance is expected to cover the full TWQR network in 2027.
🌐 PPRO launches an industry council to develop technical standards for local payments in agentic commerce. Founding members include BLIK, EPI, Bancontact Company and DIAS, focusing on agent identity, authorisation, consent, disputes and refunds. Read more.
GOLDEN NUGGET
When you make an online payment, do you know how many parties are involved and who they are?
Let’s break it down:
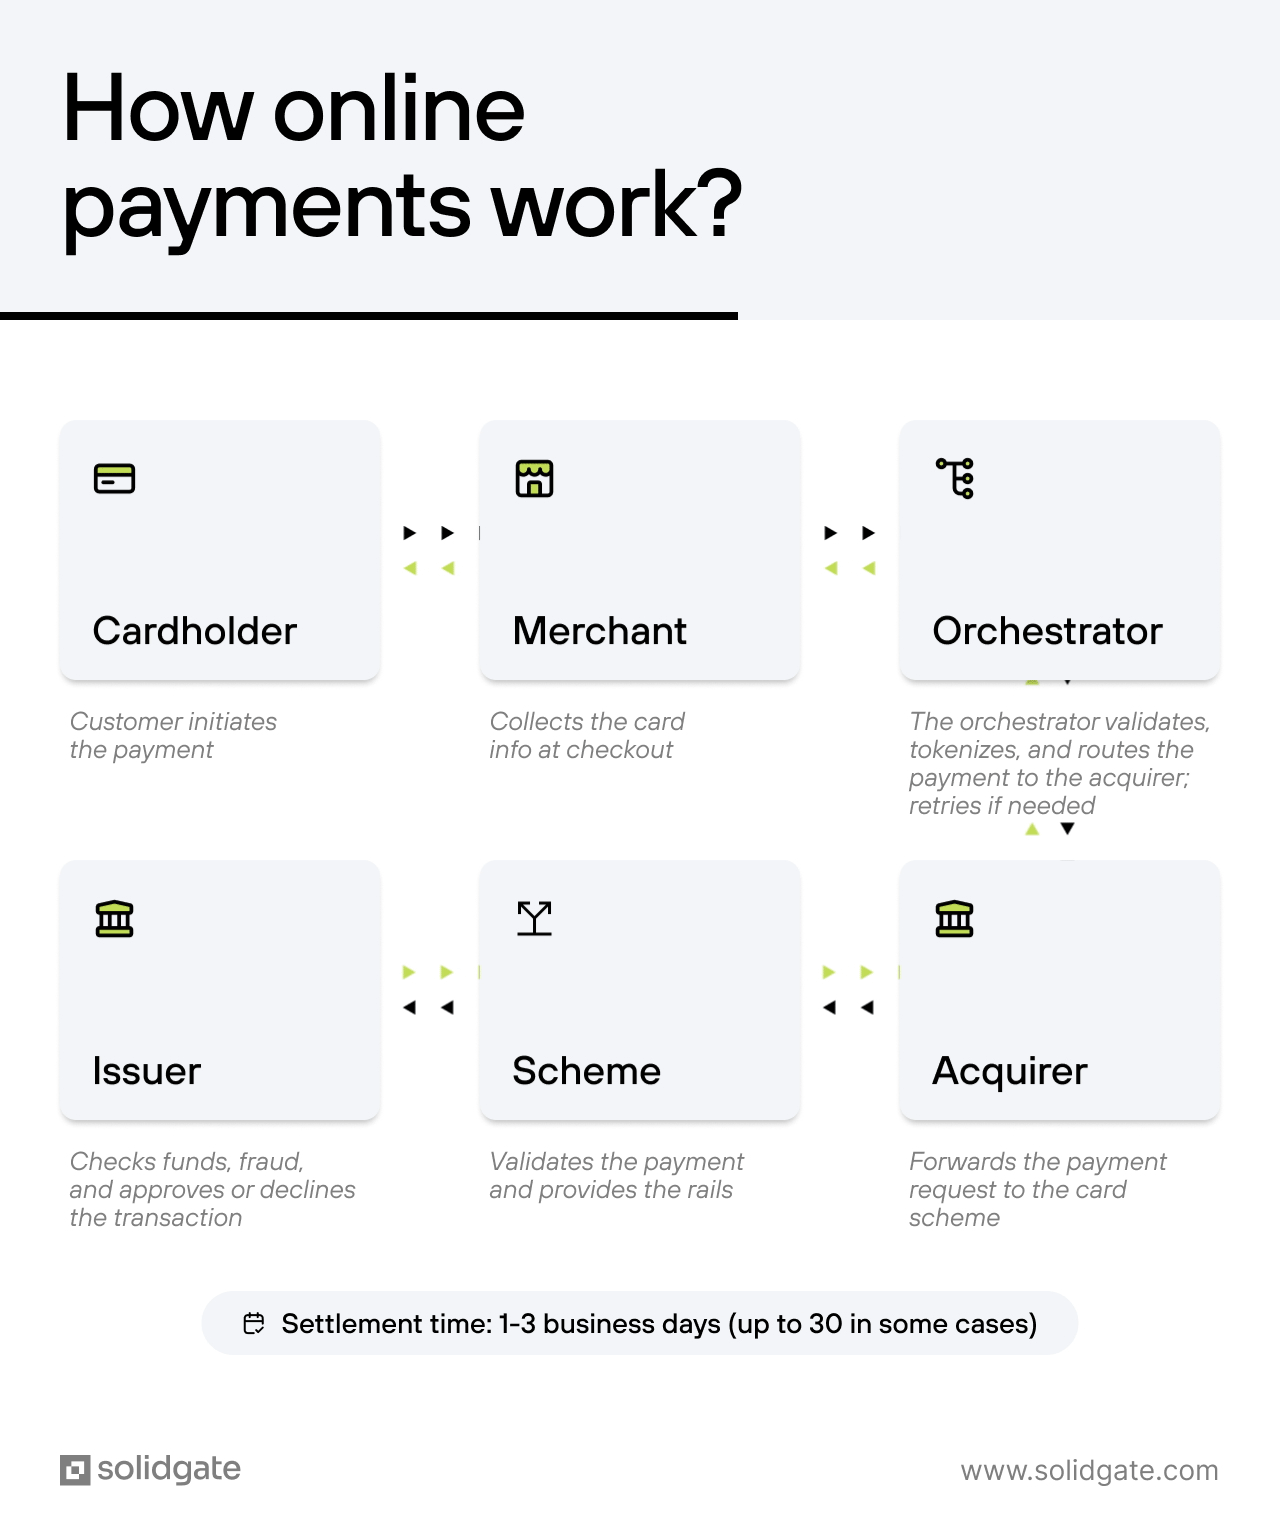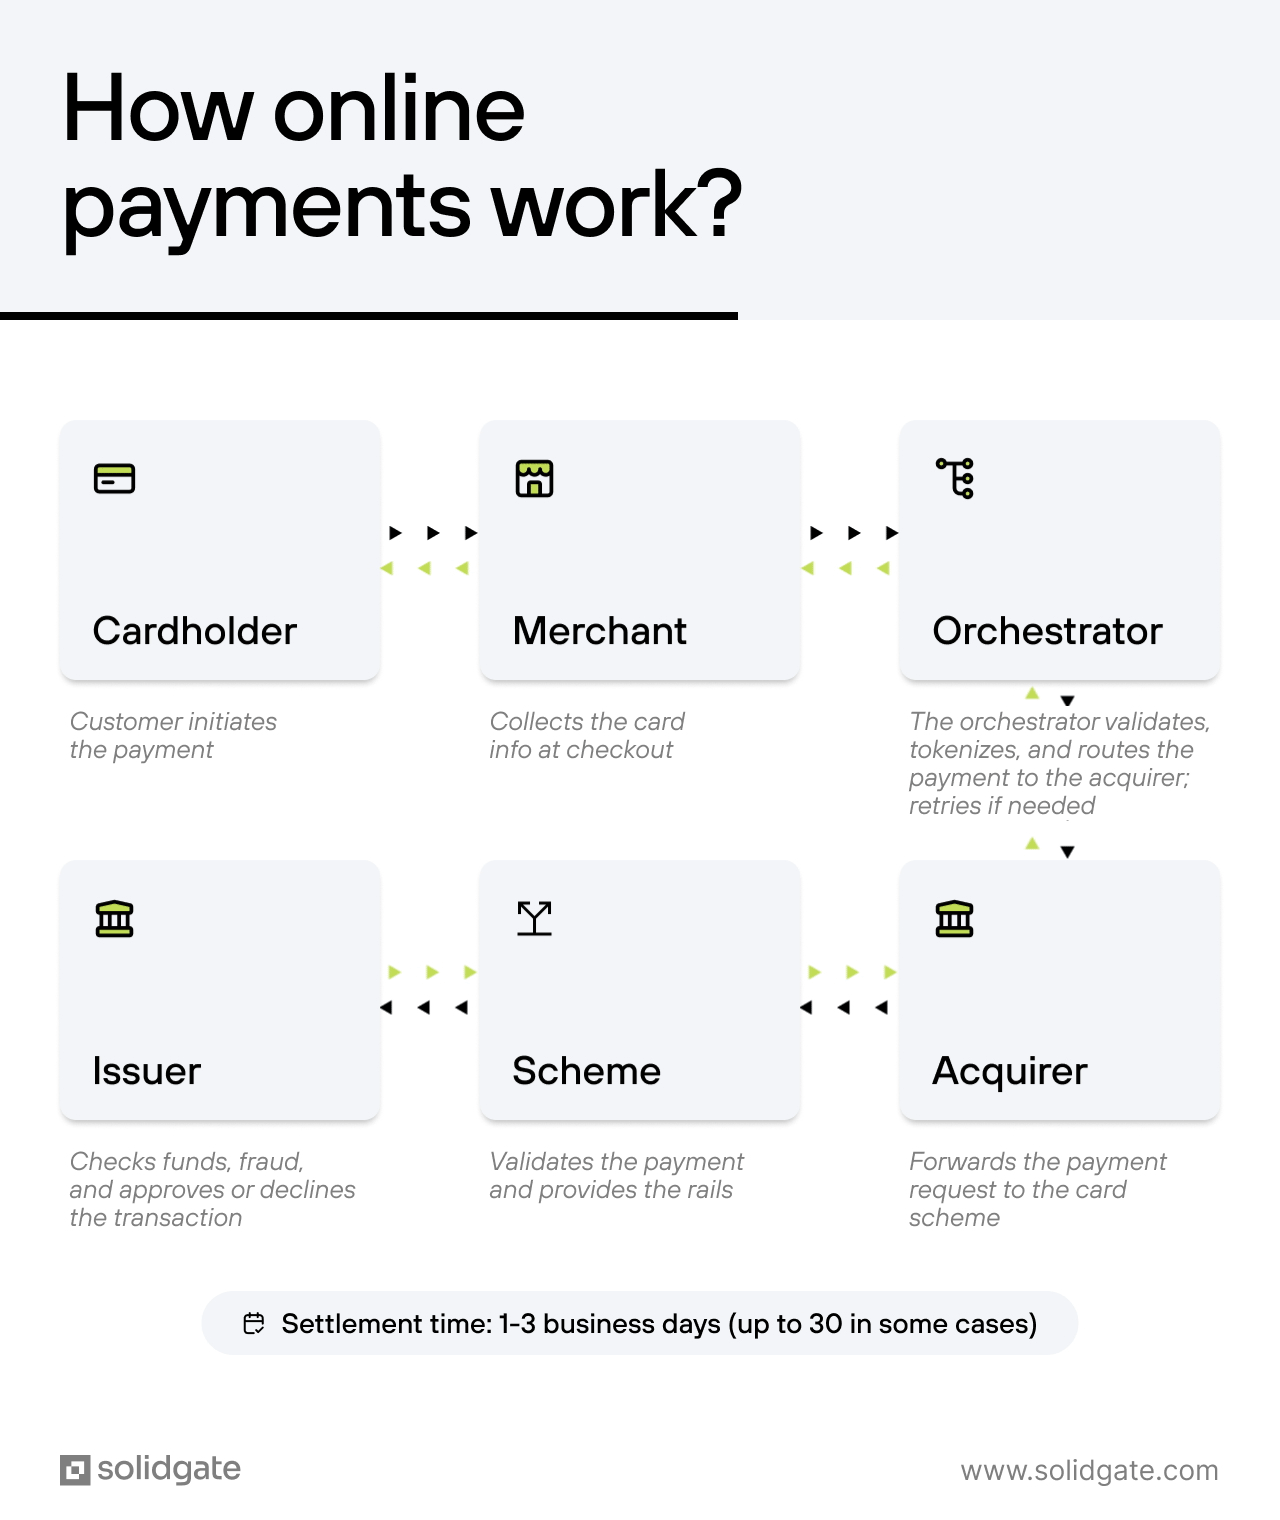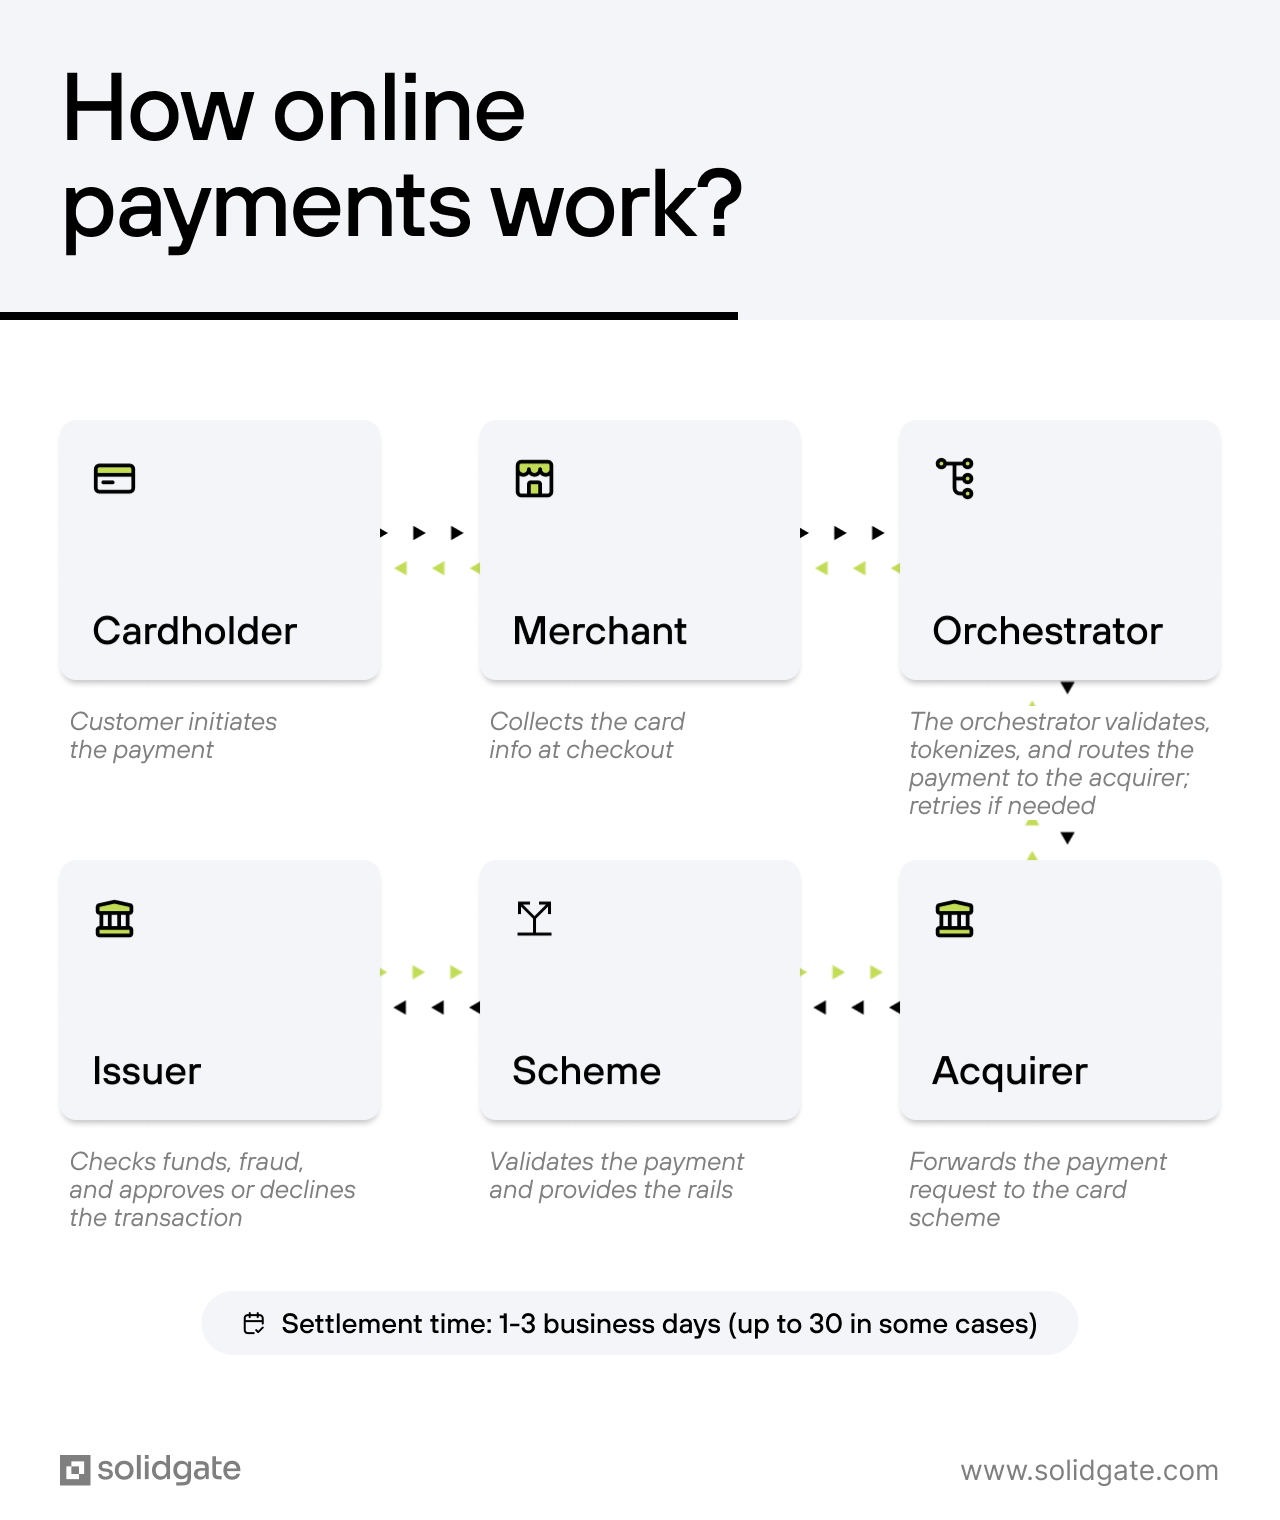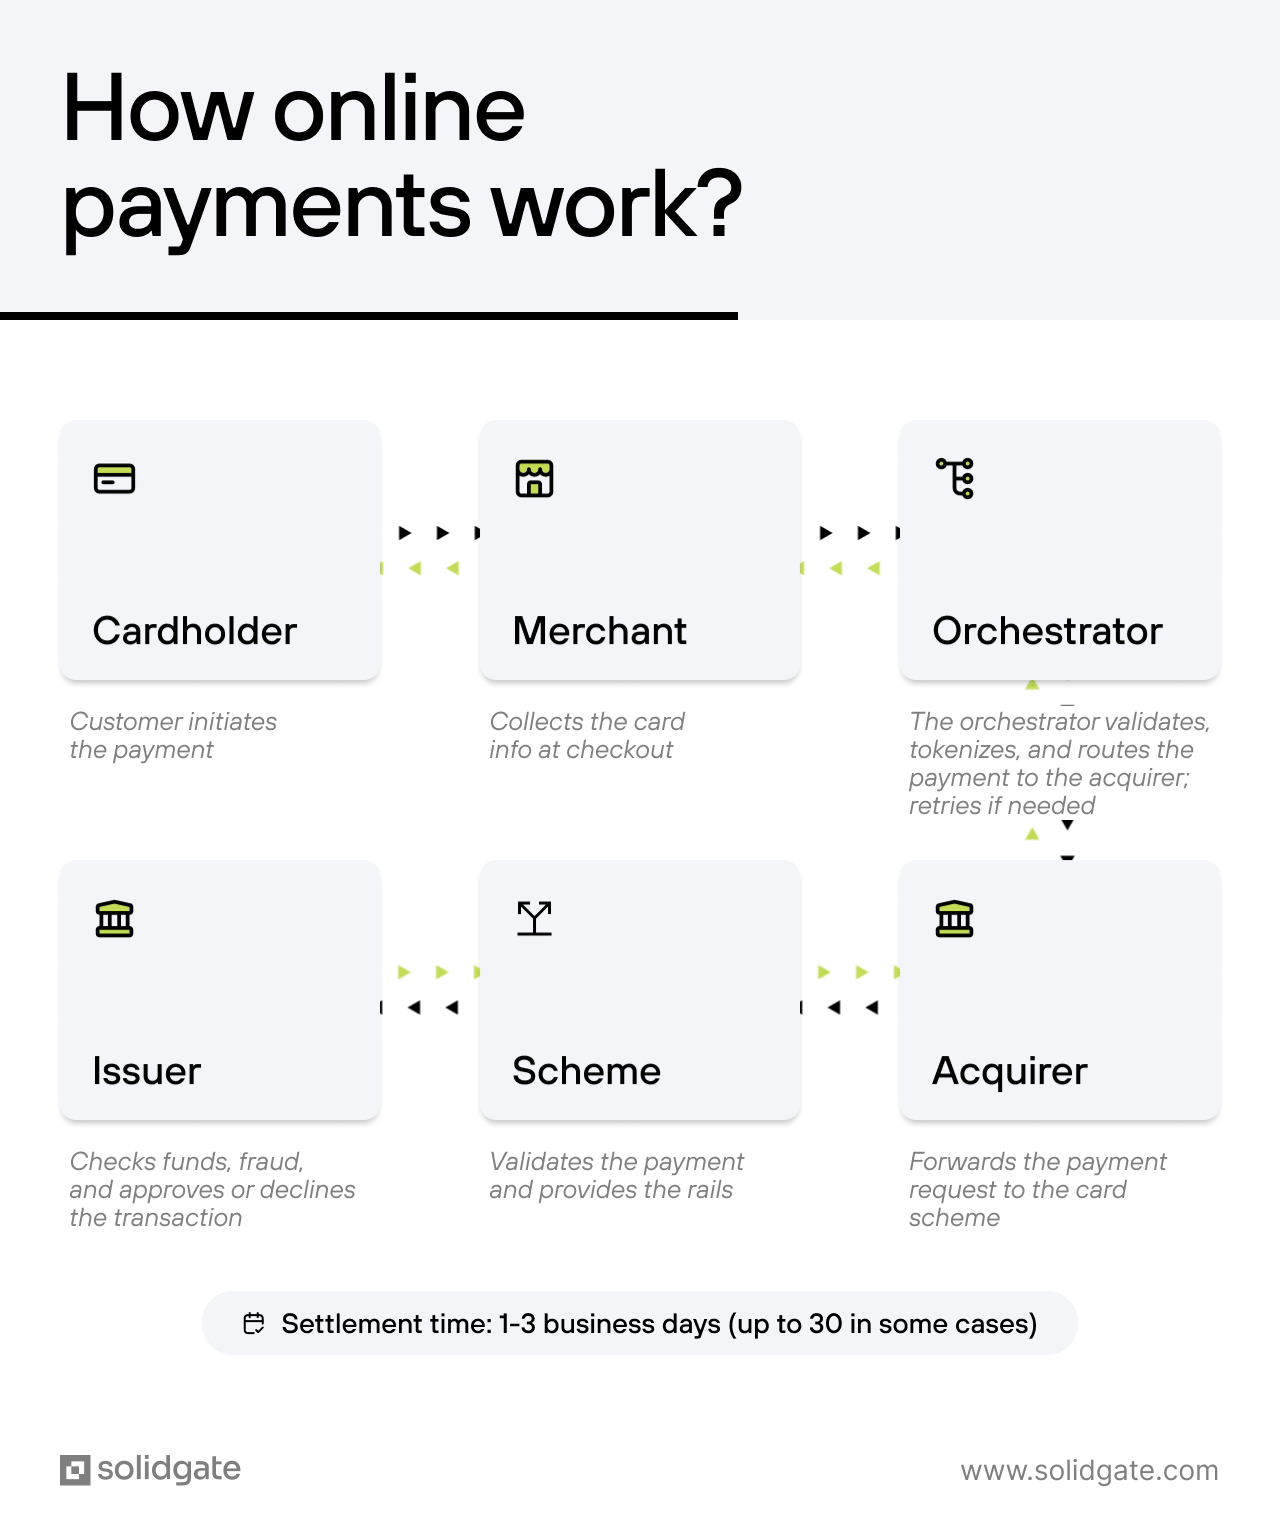
1️⃣ 𝐂𝐚𝐫𝐝𝐡𝐨𝐥𝐝𝐞𝐫 (𝐜𝐮𝐬𝐭𝐨𝐦𝐞𝐫)
First, a customer enters their card details (PAN, expiration date, CVV) on a merchant’s website or app to buy something.
2️⃣ 𝐌𝐞𝐫𝐜𝐡𝐚𝐧𝐭
The merchant collects card info via a checkout form and sends a payment request—including order details, amount, and currency—to a Payment Orchestrator.
3️⃣ 𝐎𝐫𝐜𝐡𝐞𝐬𝐭𝐫𝐚𝐭𝐨𝐫/𝐏𝐚𝐲𝐦𝐞𝐧𝐭 𝐎𝐫𝐜𝐡𝐞𝐬𝐭𝐫𝐚𝐭𝐢𝐨𝐧 𝐏𝐥𝐚𝐭𝐟𝐨𝐫𝐦 (e.g. Solidgate)
The Payment Orchestrator links merchants and providers, routing transactions efficiently by validating card data, choosing optimal acquirers, handling retries, and managing 3DS if needed.
4️⃣ 𝐀𝐜𝐪𝐮𝐢𝐫𝐞𝐫 (e.g. Adyen, Worldpay)
The acquirer enables card payments by receiving and forwarding requests through card schemes, acting as the merchant, and settling funds once authorized.
5️⃣ 𝐂𝐚𝐫𝐝 𝐒𝐜𝐡𝐞𝐦𝐞 (Visa, Mastercard)
Card schemes serve as the “payment rails” linking acquirers and issuers, routing transactions via the card BIN and performing risk, fraud, and compliance checks.
6️⃣ 𝐈𝐬𝐬𝐮𝐞𝐫’𝐬 𝐁𝐚𝐧𝐤 (e.g. 𝐂𝐡𝐚𝐬𝐞, 𝐁𝐚𝐫𝐜𝐥𝐚𝐲𝐬)
The cardholder’s bank steps in to do a quick background check: Is the card real? Are there enough funds or credit? Does anything look suspicious?
If all’s clear, it gives the green light with an authorization code. If not, it shuts it down with a reason.
The merchant gets the answer—approved or declined—and if it’s a yes, the order moves ahead. The actual money follows behind, settling in the next couple of business days.
🔁 𝗧𝗵𝗲 𝗣𝗮𝘆𝗺𝗲𝗻𝘁 𝗙𝗹𝗼𝘄: Cardholder → Merchant → Orchestrator → Acquirer → Scheme → Issuer → Scheme → Acquirer → Orchestrator → Merchant
💵 𝗦𝗲𝘁𝘁𝗹𝗲𝗺𝗲𝗻𝘁 𝘁𝗶𝗺𝗲 can range from 𝟭 𝘁𝗼 𝟯𝟬 𝗱𝗮𝘆𝘀, depending on:
► Payment method: Cards settle faster than bank transfers or ACH.
► Acquirer/Processor: Some process payments quicker than others.
► Card scheme: Visa, Mastercard, Amex vary, especially for cross-border transactions.
► Country & currency: International payments take longer due to conversions and regulations.
► Merchant account type: High-risk or new merchants may face delays from compliance checks.
► Transaction type: Refunds, chargebacks, and disputes take longer.
► Weekends/holidays: Most banks and processors don’t settle payments during these times.
► Clearing time: Depends on the bank’s processing speed.
Source: Solidgate. Discover more
Trusted reach among senior decision-makers in FinTech, Payments & Banking.
👉 Explore Partnership here


Comments ()