Checkout.com Brings Jaywan to UAE Merchants
Hey Payments Fanatic!
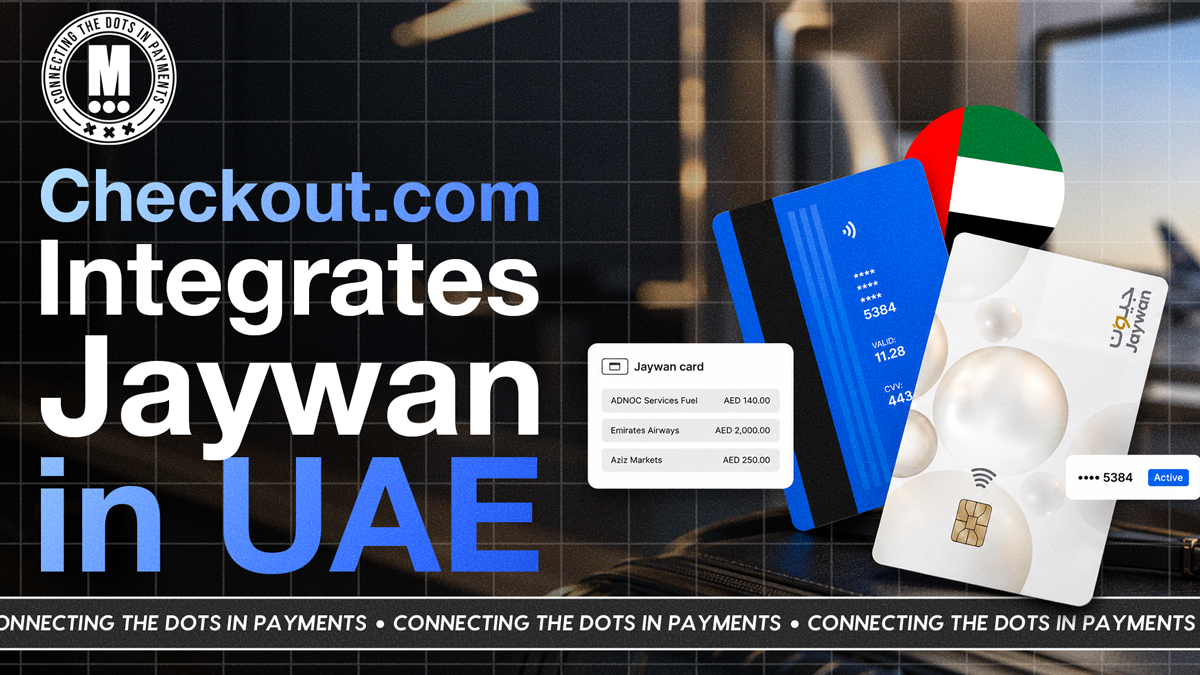
Jaywan just got a direct route into merchant payments in the UAE.
Checkout.com has integrated Jaywan into its UAE acquiring platform, giving merchants a way to accept the UAE's new domestic card scheme without building a separate integration.
And the key detail is what happens behind the scenes.
As Jaywan cards roll out, Checkout.com will recognise those transactions and route them through Jaywan's domestic rails, while merchants can keep using the same payment setup.
That's important because new payment rails only become useful at scale when merchants can access them without adding more complexity.
In this case, Jaywan is being built directly into the payments infrastructure merchants already use.
It may not change what shoppers see at checkout, but it changes what happens underneath it.
Here’s what else is happening in payments today👇
See you tomorrow!
Cheers,
INSIGHTS
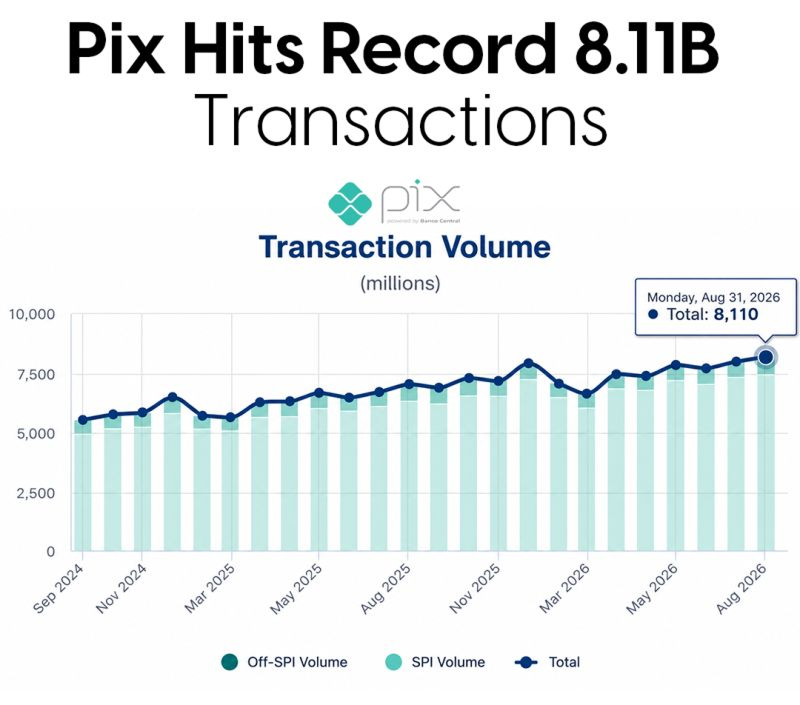
💡 From Domestic Payment Rail to Global Infrastructure. Brazil’s instant payment system has just passed 8 billion transactions in a single month, with 8.11 billion transactions and R$3.73 trillion moved in August 2026. And the momentum is continuing, with 318M+ Pix transactions recorded in a single day in September. What makes this even more interesting is the ongoing study by the Banco Central do Brasil and the European Central Bank on potentially connecting Pix with TIPS, Europe’s instant-payment settlement infrastructure. If that happens, Pix could move from being a Brazilian success story to becoming part of a much broader cross-border payments network.
NEWS
🇦🇪 Checkout.com integrates Jaywan into its UAE acquiring platform, enabling merchants to accept the domestic card scheme through local payment rails. Jaywan is operated by Al Etihad Payments, a subsidiary of the Central Bank of the UAE. The integration automatically routes Jaywan transactions domestically, reducing reliance on international rails.
🇺🇸 Mastercard launches Advanced B2B Analytics, an AI-powered platform unlocking supplier payment insights for issuers and corporates. The platform uses AI-driven acceptance propensity scoring to help issuers identify and prioritize card payment opportunities across the roughly $80T B2B payments market.
🇦🇪 Mastercard research finds UAE SMEs among global leaders in stablecoin and digital asset payments. The Dreamonomics report shows 1 in 7 UAE SMEs accept cryptocurrency, while 10% already pay business expenses in stablecoins. Two-thirds of UAE SMEs are excited about AI for their business, with 48% interested in AI-powered fraud protection.
🇺🇸 ACI Worldwide and Cognizant demonstrate strong card processing performance on AWS. BASE24-eps sustained more than double its target transaction load for 30 minutes with no failed transactions under simulated POS load. Across the full test, the system processed more than 4.6 million transactions without a single failure.
🇭🇰 Stablecoin payments firm RedotPay completes a financial audit as it presses ahead with U.S. IPO plans. Both the financial audit and an AML compliance review were conducted by Big Four firms. The company has 8.5 million users and is targeting a valuation above $5 billion for its planned listing.
🌍 Swift opens cross-border gateway to Bizum, PayID and Pix users. The integration lets banks send international payments to recipients identified by their mobile wallet or instant payment alias.
🇮🇪 Revolut Pay launches with Harvey Norman in Ireland, bringing one-click checkout to the retailer's online store. Revolut's 3.4 million Irish customers can pay using their existing balance or saved cards with automatic detail population. For the first 30 days, customers earn five times the usual RevPoints on purchases made through Revolut Pay.
🇭🇰 PhotonPay launches local collection accounts in Nigeria and Ghana, expanding its emerging market infrastructure. Global businesses can now collect Nigerian naira and Ghanaian cedi through compliant local settlement channels.
🇪🇸 Wallapop incorporates Bizum as a new payment method for both in-person and shipped transactions. Users can complete purchases using only their Bizum-linked phone number, without entering bank card details. Remote sales paid via Bizum are covered by Wallapop Protection, holding funds until the buyer confirms receipt.
🇭🇰 Hong Kong and Indonesia central banks deepen cooperation on cross-border QR payments. The HKMA and Bank Indonesia signed an MoU to establish QR code-based payment links between the two markets. The agreement aims to make cross-border transactions faster and more affordable for consumers and businesses on both sides.
🇸🇦 Aljazira Bank selects Thunes to power next-generation global remittances from Saudi Arabia. Through Thunes' Direct Global Network, Aljazira Bank customers gain real-time access to pay to billions of bank accounts and mobile wallets worldwide. Saudi Arabia has one of the highest volumes of cross-border payment activity globally.
🇬🇧 PlayStation patents an idea for a controller that can take contactless payments. The patent describes a game controller with built-in payment capabilities, making in-game purchases simpler. The filing comes as Sony prepares to phase out physical discs in 2028, shifting further toward digital commerce.
🇺🇸 Apple faces a class-action lawsuit over Apple Pay fees charged to card issuers. A U.S. federal judge certified the class action, allowing thousands of banks and credit unions to sue over allegedly unfairly high transaction fees. The lawsuit claims Apple blocks competing contactless wallet services while imposing excessive charges on issuers.
🇩🇪 Deutsche Bank and IPID announce a strategic partnership to enhance payment decision intelligence. IPID's verification, fraud and compliance signals will expand across Deutsche Bank's global payments business.
🇿🇦 Paystack launches onsite Shopify card checkout in South Africa, allowing Shopify merchants to accept card payments directly within their stores without redirecting customers to a separate payment page. The integration is designed to make checkout faster and smoother for South African online shoppers, while giving merchants access to Paystack's payment infrastructure across Shopify stores.
🌍 Vodafone teams with France's Digital Virgo on payment processing across Europe and Africa. Digital Virgo will incorporate Vodafone network APIs into payment services it provides to about 300 merchants and 150 operators. The partnership starts in Germany, Greece, Spain, South Africa and the UK with plans to expand further.
🌎 EBANX partners with NetEase Games for Latin American payment processing across Brazil, Mexico, Argentina, Chile and Peru. The integration brings local payment methods including Pix, SPEI, PagoEfectivo and Mercado Pago to NetEase Games Club. In Latin America, only one in four adults has a credit card, making local payment access critical for reaching players.
🇺🇸 Volante Technologies and Circle announce a stablecoin collaboration to bring USDC payment integration to global banks. The partnership aims to let financial institutions process USDC payments through existing infrastructure.
🇺🇸 Finalsite expands K-12 payments capabilities with its acquisition of RevTrak. RevTrak serves more than 13,000 schools, handling digital payments for meals, athletics, events and fees.
GOLDEN NUGGET
🤔 How do cards actually work?
Here is a beginner-friendly guide to how your card really works:
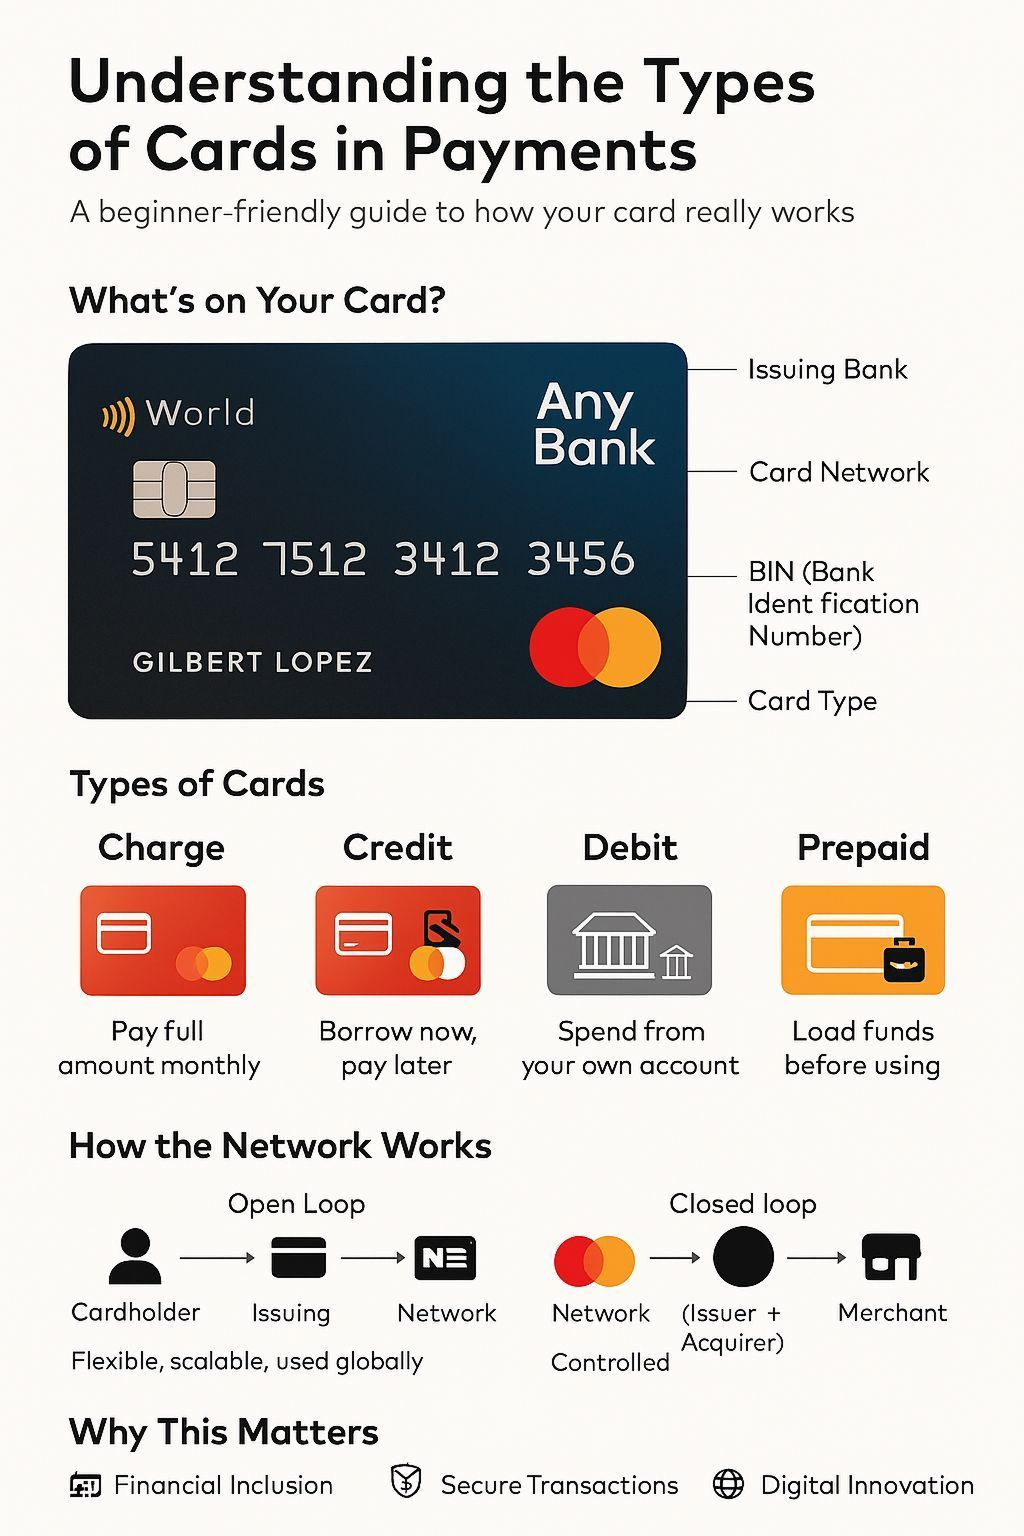
𝗪𝗵𝗮𝘁’𝘀 𝗢𝗻 𝗬𝗼𝘂𝗿 𝗖𝗮𝗿𝗱?
Most people don’t realize how much information is packed into a single card:
► Issuer: The bank that gave you the card
► Network: The technology behind the transaction, e.g. Mastercard or Visa
► BIN (Bank Identification Number): The first 6 digits, which help identify the issuing institution
► Card Type: Credit, debit, prepaid or charge
Knowing this helps you understand who’s responsible for what in each payment you make.
💳 𝗧𝘆𝗽𝗲𝘀 𝗼𝗳 𝗖𝗮𝗿𝗱𝘀 𝗘𝘅𝗽𝗹𝗮𝗶𝗻𝗲𝗱:
• Charge Cards: Spend now, pay the full balance monthly. No revolving credit.
• Credit Cards: Borrow now, pay later. You get a credit line with flexibility to pay in full or in parts.
• Debit Cards: Spend your own money directly from your bank account.
• Prepaid Cards: Load funds in advance and use them like a debit card.
𝗛𝗼𝘄 𝘁𝗵𝗲 𝗡𝗲𝘁𝘄𝗼𝗿𝗸 𝗪𝗼𝗿𝗸𝘀:
🔄 𝗢𝗽𝗲𝗻-𝗟𝗼𝗼𝗽 𝗡𝗲𝘁𝘄𝗼𝗿𝗸𝘀
(e.g. Mastercard, Visa, Discover)
► The most common model
► Involves the cardholder, issuing bank, card network, merchant and acquiring bank
► Built to scale across merchants, banks and countries globally
🔁 𝗖𝗹𝗼𝘀𝗲𝗱-𝗟𝗼𝗼𝗽 𝗡𝗲𝘁𝘄𝗼𝗿𝗸𝘀
(e.g. American Express, Diners Club)
• The issuer and acquirer are usually the same entity
• Easier to control, but harder to scale globally
• Often used in specialized or premium networks
𝗪𝗵𝘆 𝗧𝗵𝗶𝘀 𝗠𝗮𝘁𝘁𝗲𝗿𝘀:
► Financial Inclusion: Prepaid and debit products can provide important entry points into financial services
► Secure Transactions: Global card networks provide the infrastructure and standards behind payments at scale
► Digital Innovation: Cards remain part of the foundation underneath wallets, embedded finance and many modern payment experiences
Trusted reach among senior decision-makers in FinTech, Payments & Banking.
👉 Explore Partnership here
Comments ()