Mastercard Teams Up With OpenAI, but Agent Payments Are Still "Early Days"

Hey Payments Fanatic!
One story that caught my attention is Mastercard's new partnership with OpenAI.
On its Q3 earnings call, CEO Michael Miebach said Mastercard has signed a broad strategic partnership with OpenAI. It includes Agent Pay, Mastercard's payment product for AI agents, and also covers payments, joint growth in services and AI transformation.
What stood out to me was how measured he was about it.
"It is still early days, and the numbers are not yet significant in the grand scheme," Miebach said. He added that agentic transactions are growing at impressive weekly rates, and he expects holiday shopping to speed things up.
But there's more to the story.
Mastercard doesn't see one-time virtual card numbers as a long-term answer for agent payments. Miebach called them "a bridge" to fully tokenised transactions, and Mastercard is backing network tokens instead.
I read this as Mastercard wanting to shape how AI agents pay early on, while volumes are still small.
The big question is how much the holiday season moves those numbers.
Would you let an AI agent do your holiday shopping?
Here’s what else is happening in payments today👇
See you tomorrow!
Cheers,
INSIGHTS
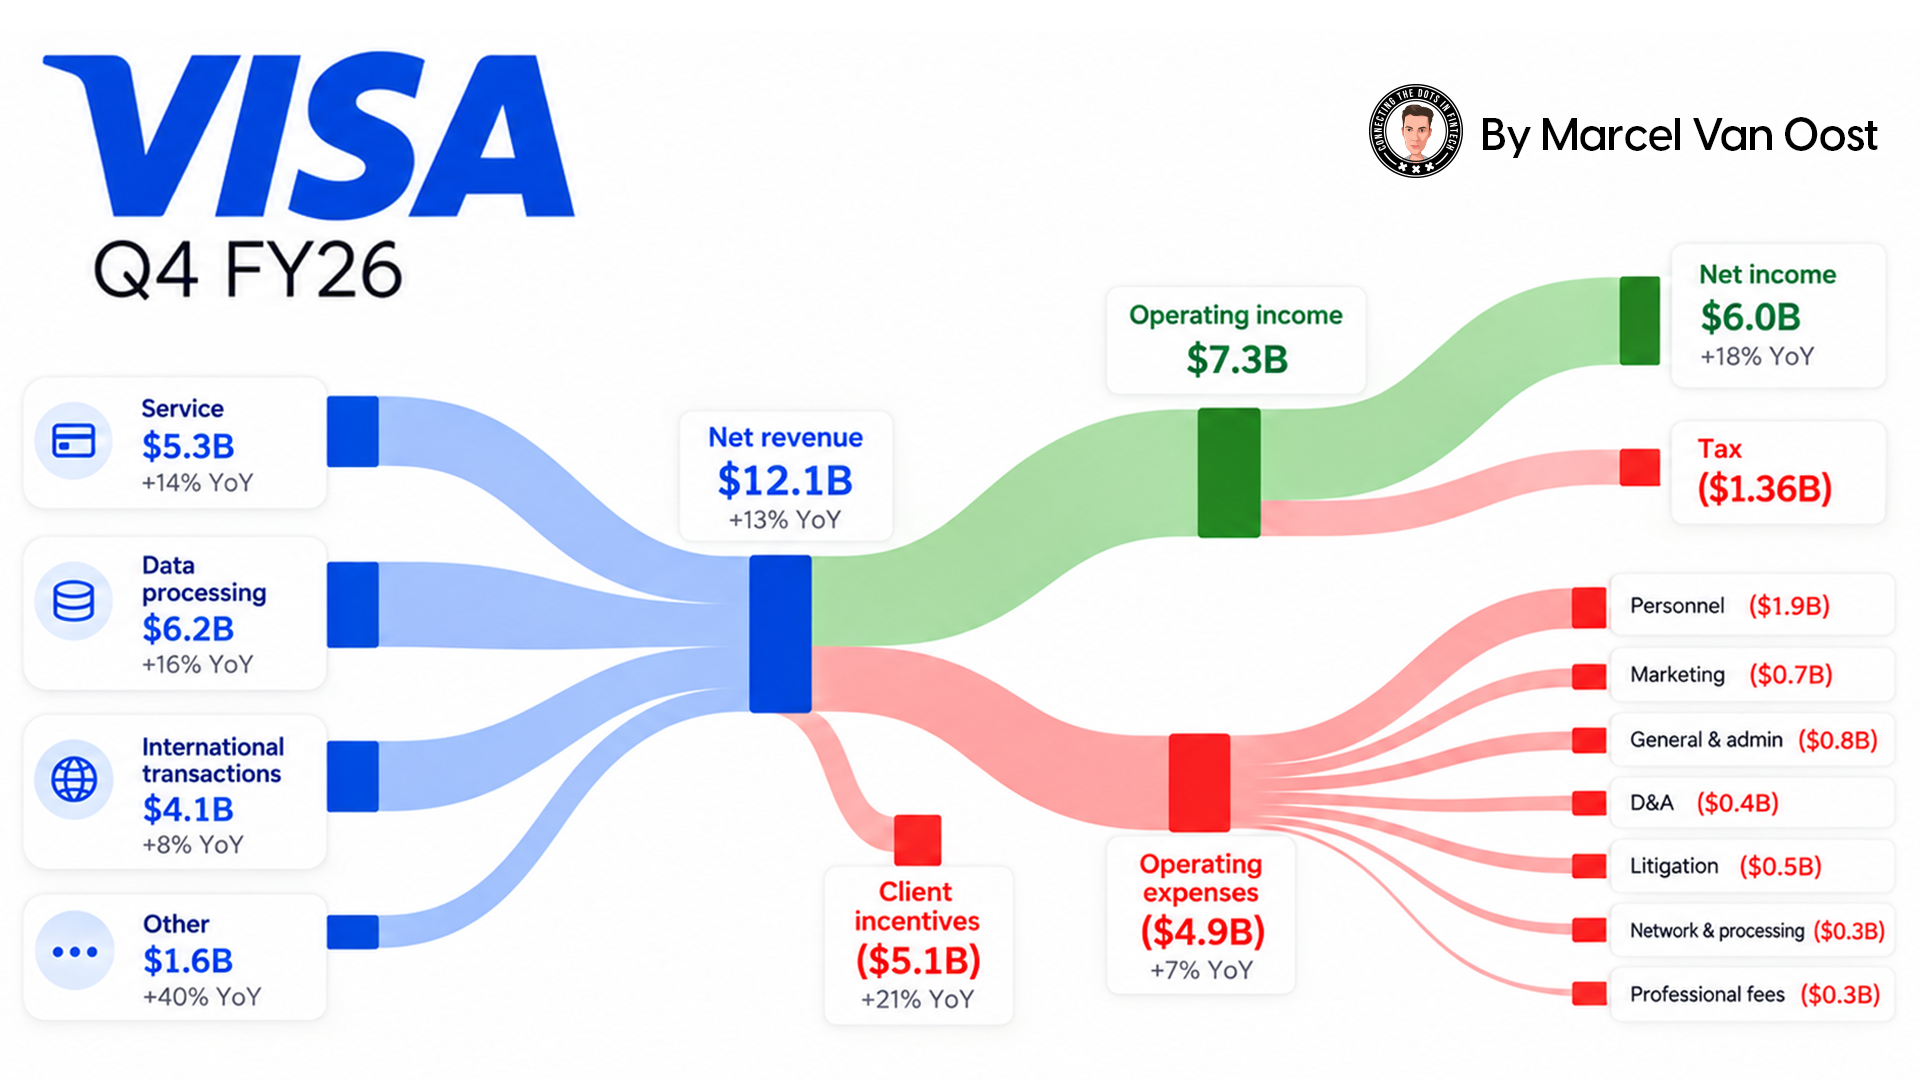
💡 Visa Q4 FY2026: Revenue Reaches $45.9 Billion as Trust Becomes the Next Growth Priority. Visa closed the year with Q4 net revenue of $12.1 billion (+13% YoY) and record full-year revenue of $45.9 billion (+15%). Cross-border volume grew 14%, while processed transactions reached 74.2 billion, up 10%. Beyond its core payments network, Visa is expanding its security business, including the planned $2.4 billion acquisition of BioCatch, as it positions fraud prevention and trust as new growth drivers. The company expects low-double-digit revenue growth in fiscal 2027, while rising client incentives remain an area to watch. Read the full results analysis here
NEWS
🇺🇸 Mastercard has signed a broad strategic partnership with OpenAI. Disclosed on the Q3 earnings call, the OpenAI partnership includes use of Mastercard Agent Pay. CEO Michael Miebach said agentic commerce is still in its early days, with volumes not yet significant despite strong weekly growth.
🇨🇳 Tencent and Mastercard sign an MoU on cross-border and agentic payments. Under the non-binding agreement, TenPay Global and Mastercard will explore letting foreign visitors pay at QR merchants in mainland China with their own wallets, and deepen remittances into Weixin. Agentic payments would follow later.
🇪🇬 Mastercard and EBank expand their collaboration on digital payments in Egypt. The strategic collaboration covers the Export Development Bank of Egypt's debit, credit and commercial cards, with Mastercard providing tokenisation, fraud and risk tools and loyalty services. New products will target specific customer segments.
🇮🇳 The Souled Store selects Unlimit to handle payments for high-demand launches. The Indian pop culture retailer now uses Unlimit across its website and app for UPI, net banking and card payments. The new payments setup is built to absorb traffic spikes during drops and sales.
🇧🇷 Pomelo expects 2027 to be the year of cross-border payments with digital assets. Speaking at Fórum Payment Anyway 2026 in São Paulo, head of business development Fabio Pompeo said scaling depends on existing consumer payment methods. Brazil's crypto volume reached about R$283B in H1 2026, according to Receita Federal data.
🇬🇧 Klarna brings interest-free instalments to Fresha's booking platform. Businesses using Fresha worldwide, including hair, beauty, wellness and fitness providers, can now offer Klarna's flexible payments for appointments. Fresha serves more than 130,000 partner businesses in over 120 countries.
🇬🇧 Sokin appoints former Corpay executive Christopher Morris as chief revenue officer. Morris, previously chief growth officer for payment solutions at Corpay Cross-Border, will lead Sokin's global commercial organisation, covering sales, onboarding, relationship management and revenue operations.
🇪🇺 Revolut Pay goes live as a checkout option on Trendyol. Shoppers on the online marketplace can pay in a single tap via account-to-account transfers, without entering card details. Revolut users earn 5x RevPoints on purchases until 18 November.
🇨🇳 Thunes and UnionPay International raise instant payout limits into China. Thunes clients can now send instant payouts to UnionPay cards at 79 major Chinese banks, up to $10,000 per recipient per day. Sending corridors include Indonesia, Thailand, Australia, New Zealand and the US.
🇸🇳 Visa signs an MoU with Senegal to develop digital payments. The two-year agreement with the ministry of telecommunications and digital affairs will explore person-to-government and government-to-person payments, cybersecurity and regulatory cooperation. It is Visa's first partnership with a Senegalese government institution.
🇨🇳 Tencent and UnionPay International sign an MoU on remittances into China. TenPay Global and UnionPay International will explore two-way remittance solutions in their first remittance partnership. TenPay Global already handles remittances into Weixin wallets from more than 150 countries and regions.
🇭🇰 XTransfer partners with Bank of China (Hong Kong) on cross-border payments. Signed at Hong Kong FinTech Week, the cooperation agreement combines BOCHK's settlement and FX capabilities with XTransfer's B2B network. It covers global collections, payments and FX for businesses in Hong Kong and other markets.
🌎 LianLian Global and Cobre partner on China–Latin America payments. LianLian clients gain access to Cobre's local payment rails in Latin America, while Cobre clients can pay out into China through LianLian's licensed network. Both plan to add further corridors.
🇮🇳 Razorpay receives a final IFSCA licence for cross-border payments from GIFT City. The final PSP licence follows in-principle approval in April and covers global investing, international collections, foreign currency transfers and multi-currency accounts. Integrations with RBL Bank and ICICI Bank are already live.
🇪🇸 CaixaBank lets customers pay in instalments in stores with Apple Pay. Holders of CaixaBank and imagin credit cards can split in-store purchases made on iPhone into plans of two to 12 months, chosen before or after paying. Plans are managed in the CaixaBank app.
🇺🇸 Navro expands its US regulatory footprint with a Texas licence. The Texas Department of Banking has granted the payments firm a money transmitter licence. Navro already holds licences in Delaware, Florida and Washington D.C., alongside e-money authorisations from the FCA and the Central Bank of Ireland.
🇨🇦 Pateno Payments completes acquisition of XTM's EveryDay platform. The platform lets Canadian businesses, mainly in hospitality, distribute tips and other payments digitally, and will be rebranded as GratiaPay. The Ontario Superior Court approved the asset sale under XTM's creditor protection proceedings.
🌐 AI agent Instinct briefly stopped replying on WhatsApp after a payment error. Founder Noah Shinn said a configuration issue interrupted payments to one of the company's service providers. Service has been restored. Shinn says the agent, which books travel and reservations, is approaching $1B in annualised transaction volume.
🇬🇧 Paysafe appoints gaming industry veteran Rob Schonfeld as chief revenue officer. Schonfeld will lead Paysafe's global revenue organisation, including sales, partnerships and commercial strategy. He was most recently chief business officer at Ludeo and previously global revenue officer at Activision Blizzard.
GOLDEN NUGGET
Your client sends $1,000. You receive $911.
And nobody can tell you where the other $89 went.
The new way to get paid - MassPay
A bank you've never heard of takes a cut. Then another. Your money gets converted twice, and you pay a spread each time. Nobody asks you, and nobody tells you.
You're not imagining it. In a survey of 6,700+ people across 10 countries, 4 in 10 said the final amount was different from what they expected.
And that's the good outcome.
Get one digit wrong in the account details and the money simply doesn't arrive. It bounces back through the same chain of banks, pays fees again on the way, and turns up a week later as a rejection with no explanation. You find out only because nothing showed up.
This isn't a niche problem.
According to the World Bank, sending $200 across borders through a bank costs close to 15% on average. The global target is 3% by 2030. Digital services already average about 4.6%, so the cost is in the route the money takes.
And the system was built for the sender.
SWIFT reports that most payments now reach the receiving bank within an hour. But by the G20's own measure, only about 60% reach the customer's account that fast. The delay happens at the very last step, the one the person waiting for the money actually feels.
→ The sender gets a confirmation.
→ The receiver gets silence.
And that person is increasingly a freelancer, a creator or a contractor:
• 63% send or receive money internationally (vs 27% of other workers)
• 11% lost or turned down work over payment delays, fees or uncertainty
That's nearly 3x the rate of everyone else. That's lost income.
Then there's the account itself. Many people are still told they need a traditional bank account, in a specific country, set up a specific way, just to receive money they already earned.
Meanwhile, the World Bank's Findex counts 1.3 billion adults without a financial account. Roughly 900 million of them already own a mobile phone. The device is in their hand. The payment just hasn't caught up.
None of this needs to be invented. It needs to become the expectation:
1️⃣ You choose how you get paid: bank, wallet, card, or cash pickup
2️⃣ One conversion, at a rate you see upfront
3️⃣ Details checked before the money moves
4️⃣ Fast where the infrastructure allows it
5️⃣ Visible to both sides
The key insight is simple:
A payment is only finished when the person actually has the money, in full, in the way they chose to receive it.
You can track a $12 package across the ocean in real time.
You should be able to track your paycheck.
Source MassPay. Read the full piece
Trusted reach among senior decision-makers in FinTech, Payments & Banking.
👉 Explore Partnership here


Comments ()